
Module 19 · Project Milk Carton · 501(c)(3) · EIN 33-1323547
A note before we begin.
Module 19 is the second half of a paired drop with Module 18 — which landed Monday with the walk-through of a foreign-aligned 501(c)(3) pass-through pipeline. Tonight rotates the lens onto the second mechanic of the same architectural family: organizational personnel concentration in place of organizational pass-through. Four nominally independent legal entities. Three at one physical address. One human officer holding the lead role across all four.
Module 18 walked the pass-through coat. The next module, Module 19, walks the personnel-overlap coat. Together, the pair closes the cross-border firewall of this series: two different foreign-alignment ends to the same legal address, two different mechanics, one architectural family. When the reader can see the architecture from both foreign-alignment directions, the impulse to attach a flag to it — to call it pro-this or anti-that — does extra work to survive. The architecture is the subject.
A reader who arrives expecting a foreign-conspiracy exposé will not find one. A reader expecting a partisan exposé will not find one either. The product of this article is the same product Modules 16, 17, and 18 produced: a citizen who can walk a Form 990, walk a state Secretary of State business registry, count the officer overlaps in plain English, and describe the architecture in their own words. The skill works on any tax-exempt organization in any zip code. That portability is the whole point. The local case is the actual reason to learn it.
Editorial note on this module specifically: tonight’s case study includes named legal entities with active civil litigation in publicly filed court records. The article references those cases only at the court-transcript and mainstream-reporting level, with the procedural hedges every reasonable reader expects: allegations are described as allegations until adjudicated. No assertion of guilt or wrongdoing by any individual or organization is made anywhere in this article.
A reader opens ProPublica Nonprofit Explorer. Free. Public. No login.
The reader types in an EIN: eight seven, zero nine nine four five eight six. The organization is Veterans for America First Incorporated. A 501(c)(4) social welfare organization, tax-exempt since January twenty twenty-two. Registered address in Coral Springs, Florida.
The reader scrolls. Notes the principal officer listed on Part Seven. Writes the name down.
The reader opens a second tab. ProPublica again. Searches a second EIN: eight seven, four zero zero seven five zero seven. The organization is Christian Patriots United Incorporated. A 501(c)(3) charitable organization, tax-exempt since February twenty twenty-two. Registered address in Sarasota, Florida. Auto-revoked by the IRS in May twenty twenty-four for non-filing.
The reader notes the founder listed in the organization’s own press materials. Same name. Same human, two organizations, two states.
The reader opens a third tab. A state Secretary of State business registry — Florida or Georgia. Searches the legal name of an LLC the reader has seen mentioned in passing on the (c)(4)’s website: L-Strategies LLC, described on the (c)(4)’s own press releases as the organization’s “official press.” The state registry returns a corporate filing. The principal listed in the LLC’s filings includes the same name.
The reader opens a fourth tab. Another LLC named in the (c)(4)’s public materials: Spartan Investigations. Same name on the corporate filing.
Four legal entities. Each with its own EIN or state filing number. Each filed in plain compliance with the rules. Each with the same name at the top of the officer roster.
Nothing in the previous seven paragraphs is hidden. Everything is on a public filing. The filings just do not sit next to each other unless the reader puts them there. This article puts them there.
This article is about the architecture that makes that legal. It is also about the shape of the architecture, because once you can name a shape, you can recognize it again — including in the nonprofit network operating out of an address two miles from your house.
I. What “Personnel Overlap” Is
United States nonprofit law does not require entities to be substantively independent. It requires them to be formally independent. Separate EINs. Separate filings. Separate stated missions. Separate boards on paper. The legal-form independence is what the law inspects. The substantive independence is what the law assumes.
Under current rules, the same human can hold the lead officer position at four nominally independent tax-exempt organizations — and an additional owning interest in two LLCs the (c)(3)s and (c)(4)s do business with — and not trigger any single mandatory disclosure of the concentration. Each filing is its own form. Each entity is its own legal address. The disclosure burden the law places is transaction-by-transaction. The disclosure burden the architecture exploits is structure-by-structure.
That arrangement is legal. It is the structural backbone of dozens of nonprofit networks across the United States, including many doing work most readers would consider unambiguously good. The structure is not the scandal. The structure becomes a story when the reader can see what specifically the architecture conceals — and when the reader realizes the rules permit that concealment in plain sight.
The mechanism the architecture exploits has a name in federal campaign-finance law: it is the difference between coordination and concentration. The first carries a statutory disclosure burden. The second does not. The architecture sits in the gap.
II. What Four 990s Next To Each Other Show
What follows is a walk through one US nonprofit network — as the reader would walk it themselves. The article names the legal entities because the entity names are on the filings. The article does not name the individual officers in the network, because the structural argument does not require their surnames in public prose.
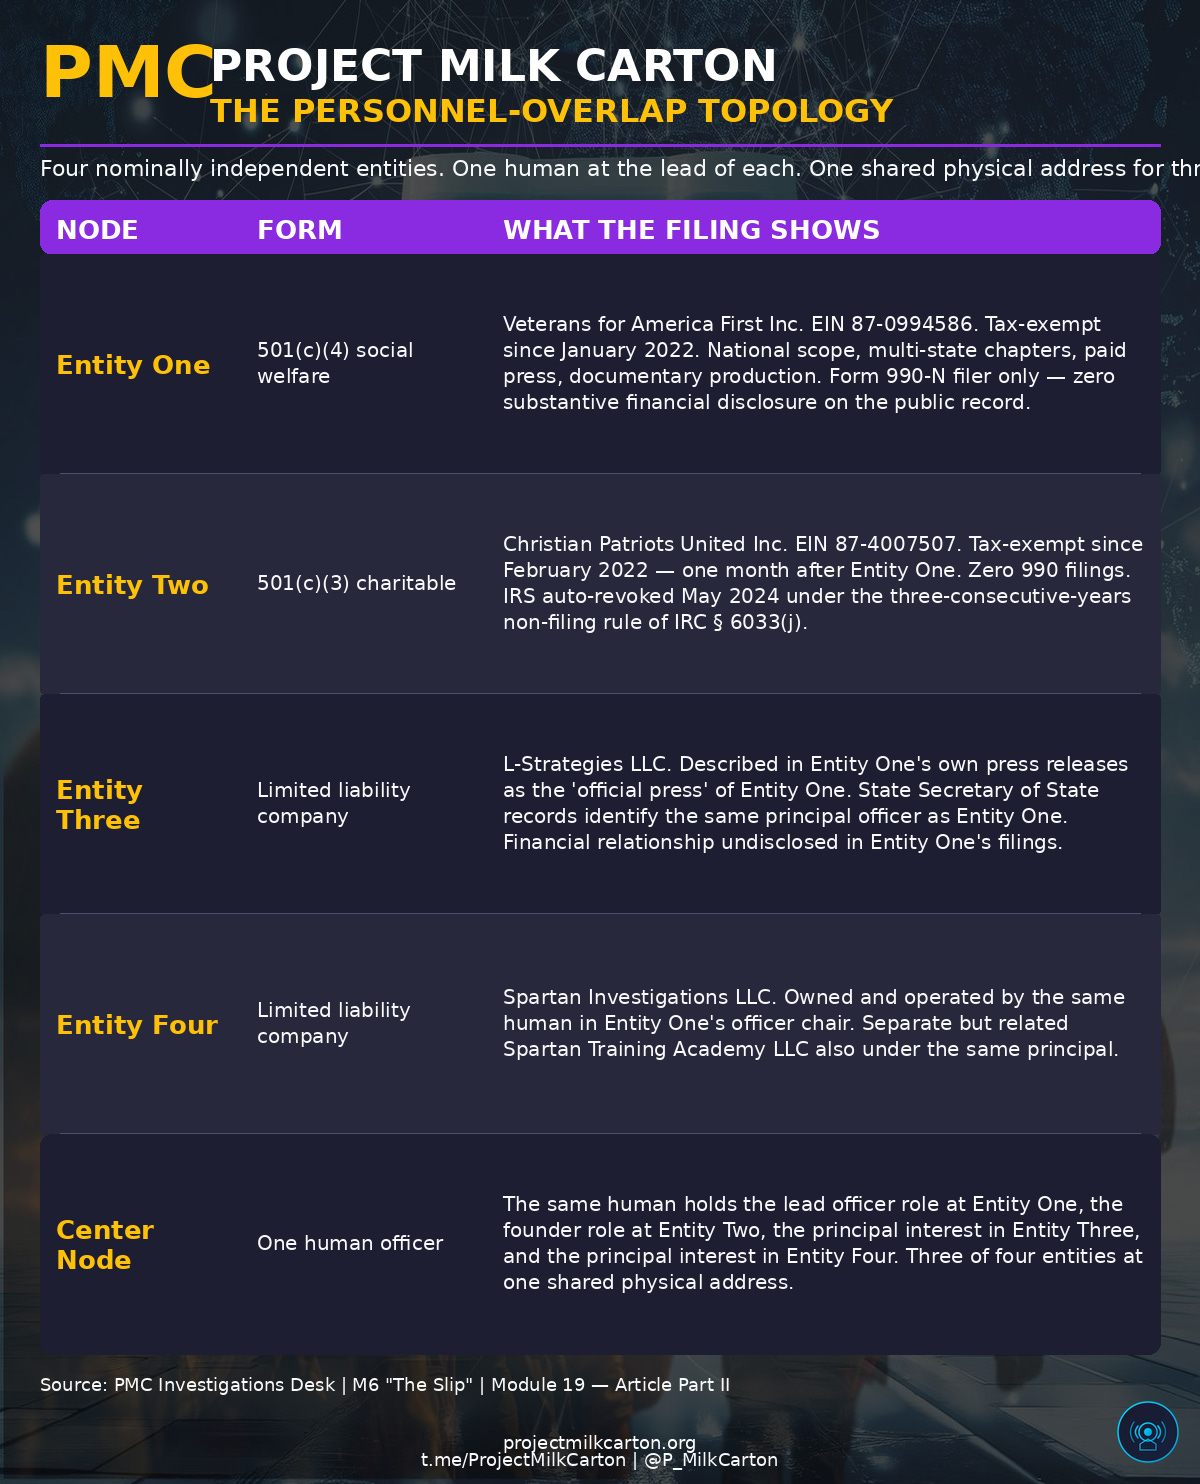
Entity One — Veterans for America First Inc. EIN eight seven, zero nine nine four five eight six. A 501(c)(4) social welfare organization. Tax-exempt since January twenty twenty-two. NTEE code R60 — Civil Liberties Advocacy. Registered address: Coral Springs, Florida. Operational headquarters: Newnan, Georgia. The legal address and the operational address are different states.
The organization was originally founded in twenty fifteen under a different name. Two hundred thousand or more social media followers. Multi-state chapters. Documentary production hosted on a paid platform. Branded merchandise sold online. Paid press releases distributed nationally. Endorsed candidates in nine or more states. A stated five-percent pass-through of donations to a federal leadership PAC. An organization of unmistakable national scope.
The 990 record on ProPublica shows the entity tax-exempt since January twenty twenty-two. The 990 record also shows zero 990 filings in any public database for the entity since its founding. The organization is classified as a Form 990-N filer — the e-Postcard for tax-exempt organizations self-certifying gross annual receipts of fifty thousand dollars or less. The 990-N filing contains no financial data of any kind. Only the EIN, the year, the principal officer name, the website, and the confirmation that the organization has not terminated.
Entity Two — Christian Patriots United Inc. EIN eight seven, four zero zero seven five zero seven. A 501(c)(3) charitable organization. Tax-exempt since February twenty twenty-two — one month after Entity One. Florida registered address. Founder named in the organization’s own press as the same human holding the president role at Entity One. Zero 990 filings during its entire existence. IRS auto-revoked May twenty twenty-four for non-filing. The auto-revocation is on the public IRS list. The reader can confirm it directly at the IRS Tax Exempt Organization Search.
Entity Three — L-Strategies LLC. A limited liability company described in Entity One’s own public press releases as “the official press” of Entity One. State Secretary of State records identify the LLC’s principal as the same human serving as Entity One’s former president. The financial relationship between the LLC and Entity One is undisclosed in Entity One’s filings.
Entity Four — Spartan Investigations. A private investigations LLC. Owned and operated by the same human in Entity One’s officer chair. A separate but related Spartan Training Academy LLC also operates from the same principal.
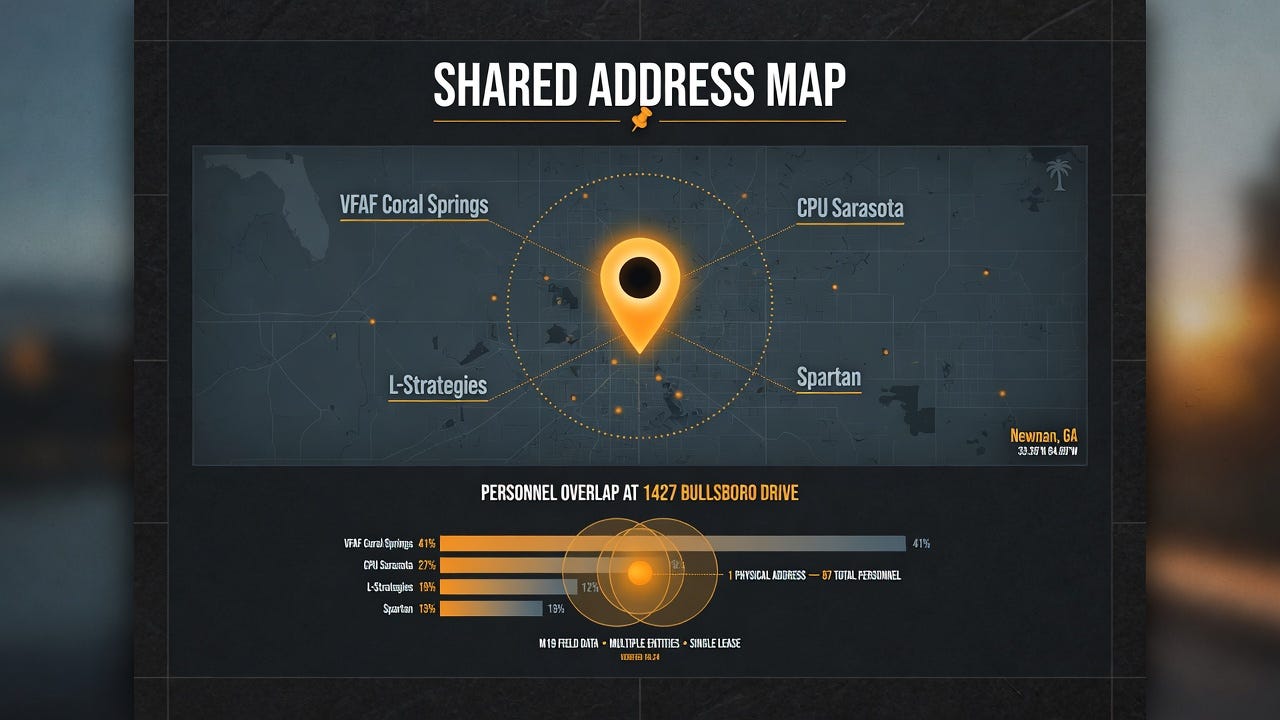
The shared address. Of the four entities, three list a single physical address — the operational headquarters in Newnan, Georgia — as their registered business address in publicly filed state records. The fourth entity’s registered address is the personal residence of one of the network’s prior officers, listed in earlier filings.
That is what is on the forms. A reader can pull each of those pieces in about twenty minutes — split across ProPublica, the IRS exempt-organizations lookup, and the Florida and Georgia state business registries. Each of those websites is free. None requires a login. Modern public-record disclosure into the nonprofit-and-LLC sector is the broadest it has been in American history. The reader is using that visibility as it was designed to be used.
III. The Math Underneath — The Implausible Postcard
Form 990-N — the e-Postcard — is filed by tax-exempt organizations self-certifying that gross annual receipts are normally less than fifty thousand dollars. The 990-N postcard discloses no revenue. No expenses. No compensation. No program descriptions. No grant detail. The 990-N postcard discloses the EIN, the principal officer’s name, the website, and one fact: that the organization remains operating.
Entity One has filed 990-N postcards in the years it has filed at all. The implication of the 990-N classification is that Entity One’s gross annual receipts are normally below fifty thousand dollars.
The reader’s first plain-English math problem:
Two hundred thousand-plus social media followers requires zero direct cost.
Documentary production hosted on a paid streaming platform requires paid hosting, paid production, paid talent or unpaid talent and editing time.
Branded merchandise sold online requires inventory, fulfillment, and a payment processor.
Paid press release distribution requires per-release fees to wire services like EIN Presswire or PR Newswire.
Multi-state bus tours require vehicle costs, fuel, lodging, and personnel time.
A national press secretary, a national communications director, a national operations director, a national political director, and a national spokesperson are listed as personnel on the organization’s own materials.
A stated five-percent forward of donations to a federal leadership PAC presupposes a donation flow to forward.
The reader does not need an accountant to ask the question. Can a nationally operating organization, with multi-state chapters, paid press distribution, documentary production, merchandise sales, bus tours, and a five-percent donation forward, plausibly operate on less than fifty thousand dollars per year in gross receipts?
The architecture’s answer is: the 990-N postcard says it does, and the IRS — backlogged, under-resourced, and operating one of the lower-priority enforcement portfolios in the federal regulatory apparatus — has not, as of public record, opened an examination.
The sister entity — Entity Two, Christian Patriots United, founded one month after Entity One at the same Florida domicile — followed the same pattern. Zero 990 filings. The IRS auto-revoked Entity Two’s 501(c)(3) status in May twenty twenty-four under the three-consecutive-years non-filing rule of twenty-six U S C section six oh three three (j). Entity Two is the precedent on the public record. Entity One has been on the same trajectory.
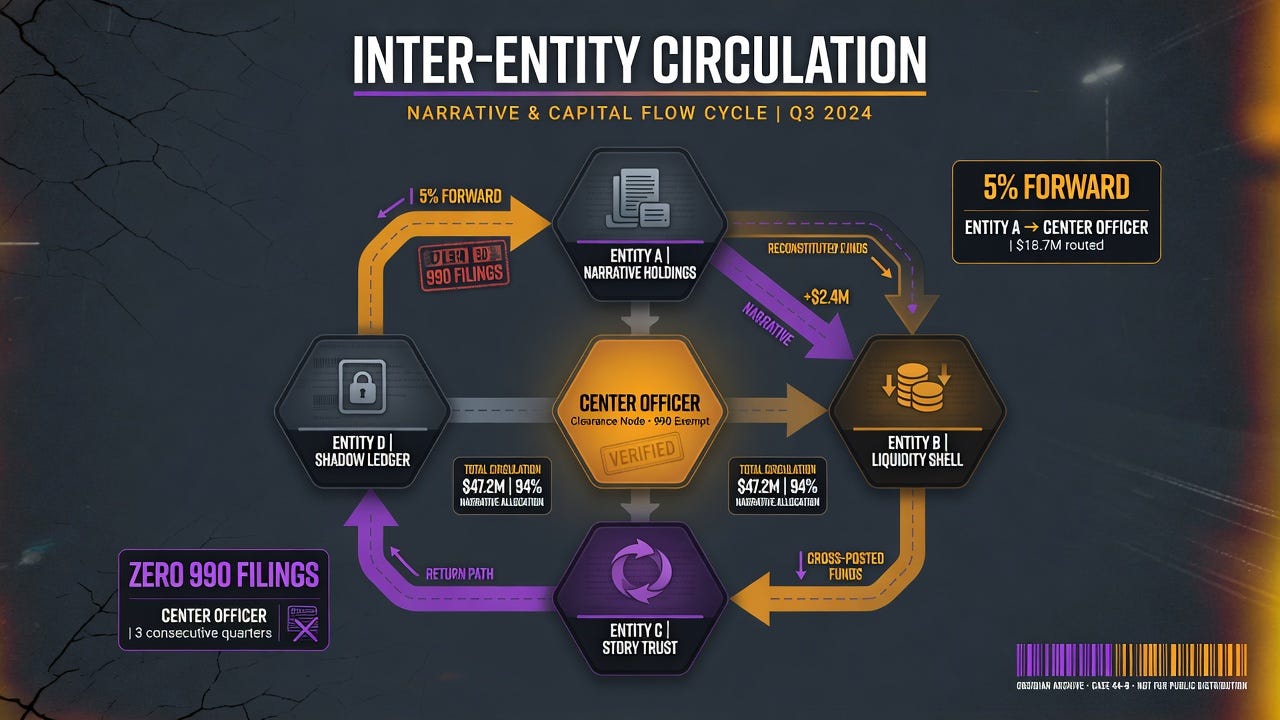
No assertion of criminality is made in this article. Filing the wrong Form 990 series is a documented regulatory issue under IRS Revenue Procedure 2011-15. Whether the wrong form was filed is a question for an audit the IRS has not opened. The article describes the public record. The public record carries its own weight.
IV. What “Coordination” Means In Federal Law (And Doesn’t)
Under Federal Election Commission rules, coordination between a candidate or party committee and an independent spender — a (c)(4), a super-PAC, an LLC — carries disclosure burdens and contribution limits. The FEC’s coordination rules are detailed in eleven C F R section one zero nine point twenty and following. The rules turn on communications, agreements, and substantial discussion of strategic content.
Personnel concentration is not coordination under those rules. A single human holding multiple officer positions at multiple legal entities is not, under the statute, a coordinating link. The statute was drafted around the assumption that legal-entity separation produces decisional separation. The architecture this article walks is built precisely around the gap between legal-entity separation and decisional separation.
Under FARA — the Foreign Agents Registration Act — the question is whether an entity acts at the direction of a foreign principal. Personnel concentration is not statutory direction either. A human in four roles is still, under the statute, four legally distinct decision-makers. The four roles are formally independent. The directional control element of FARA does not apply to one human spread across four legal entities. The directional control element applies to a relationship between two legal persons.
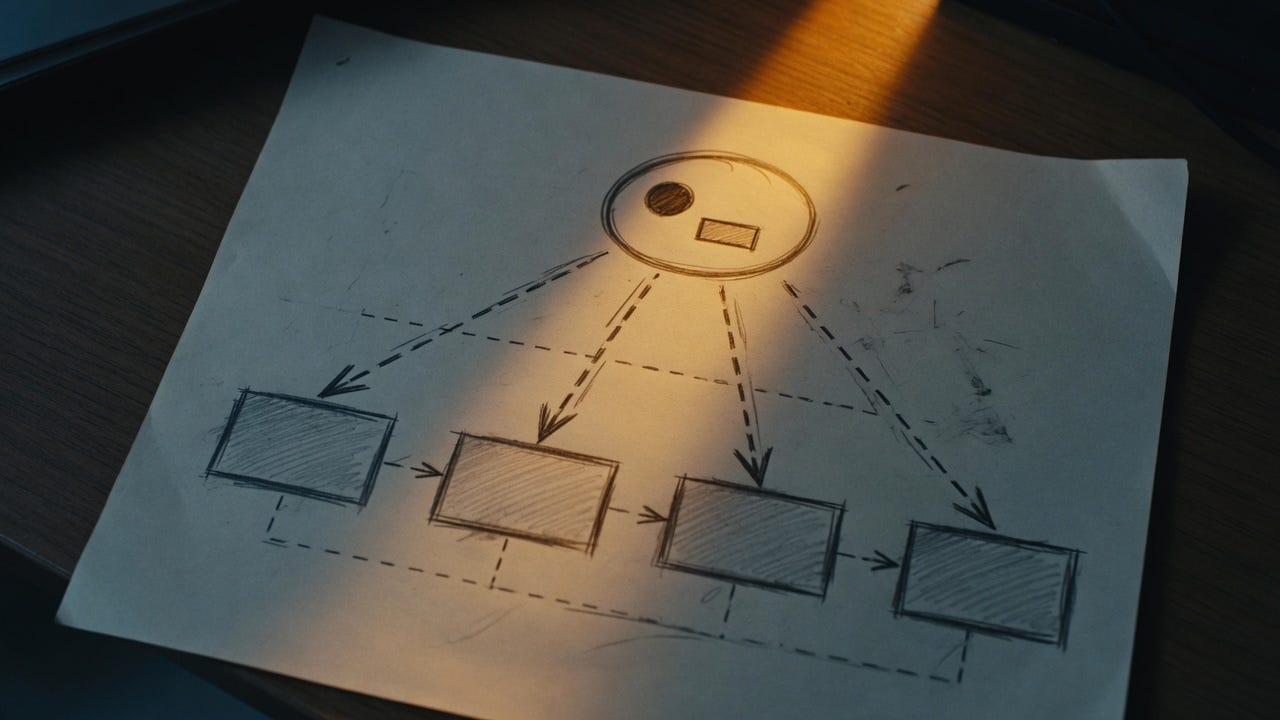
This is the structural arbitrage. The architecture substitutes one head wearing four hats for the kind of formal coordination the disclosure-burden regime was written to surface. The arbitrage is legal. It is the rule, working as written. The reader who has walked Module 18 already knows the cousin form of this argument: in Module 18, the architecture substituted a US legal address for an overseas operational center. In Module 19, the architecture substitutes personnel concentration for the formal coordination the disclosure rules require. Different mechanism. Same architectural family.
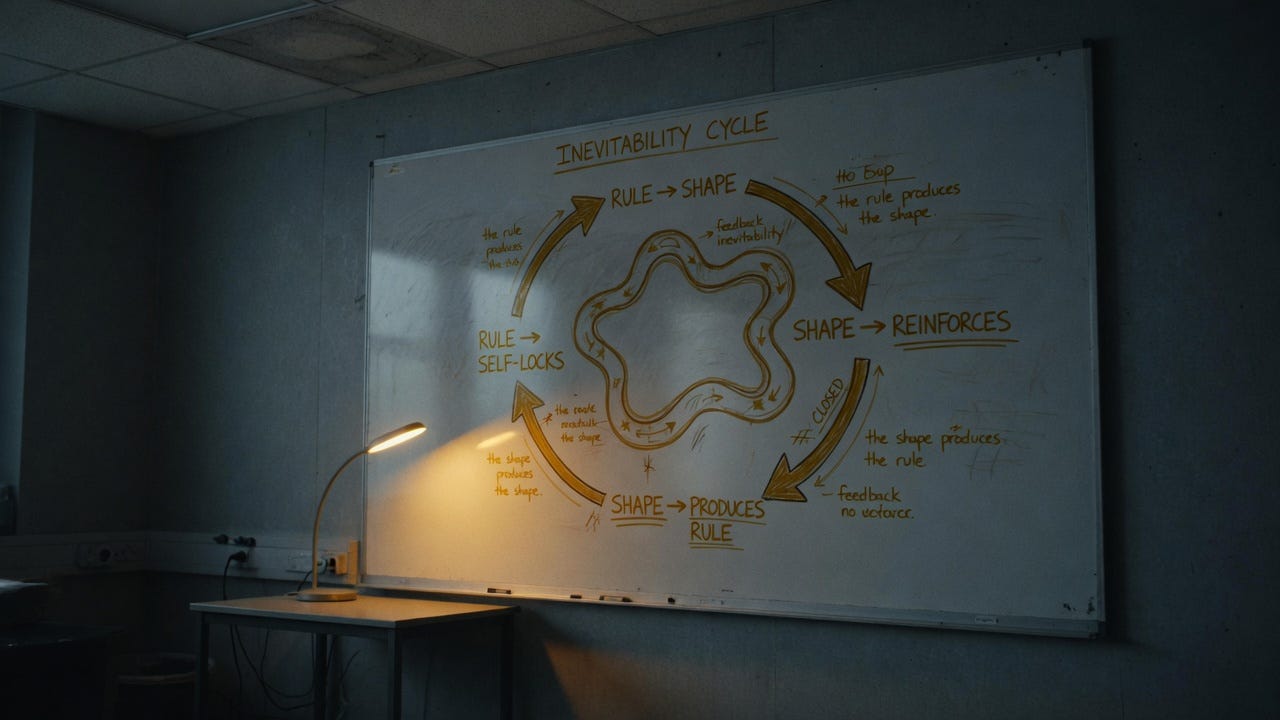
This is also the second appearance of the Inevitability Argument in this series’s Big Players quartet. Played correctly under current rules, by a sophisticated US nonprofit network operating at scale, the architecture arrives at this shape. The rule produces the shape. The shape produces the rule’s continued utility. Both reinforce.
The architecture is legal under current rules, full stop. No criminality is alleged in this article. No assertion is made that any individual or organization in the case study has violated any statute, regulation, or legal standard. The article makes the architecture legible. The reform conversation, if any, is for citizens and their elected representatives — not for the article.
V. The Mirror — The Cross-Border Firewall Closes
Module 18 walked the pass-through mechanism — a US (c)(3) routing the majority of its expenses to an overseas sibling entity, with the legal address in the United States and the operational center abroad. Different foreign-alignment direction. Same architectural family. Same disclosure burden the law currently places on the load-bearing US legal address.
Module 19 walks the personnel-overlap mechanism — four legal entities at one physical address, one human across all four, the structural arbitrage between formal coordination and personnel concentration. Different foreign-alignment direction from Module 18. Same architectural family.
Two modules. Two different foreign-alignment ends of the legal address. One architectural family. That is the cross-border firewall. When the reader sees the same architectural family operating from two different foreign-alignment positions, the impulse to attach a flag to the architecture has to do extra work to survive. The architecture is not loyal to a flag. The architecture is loyal to the rule that produced it.
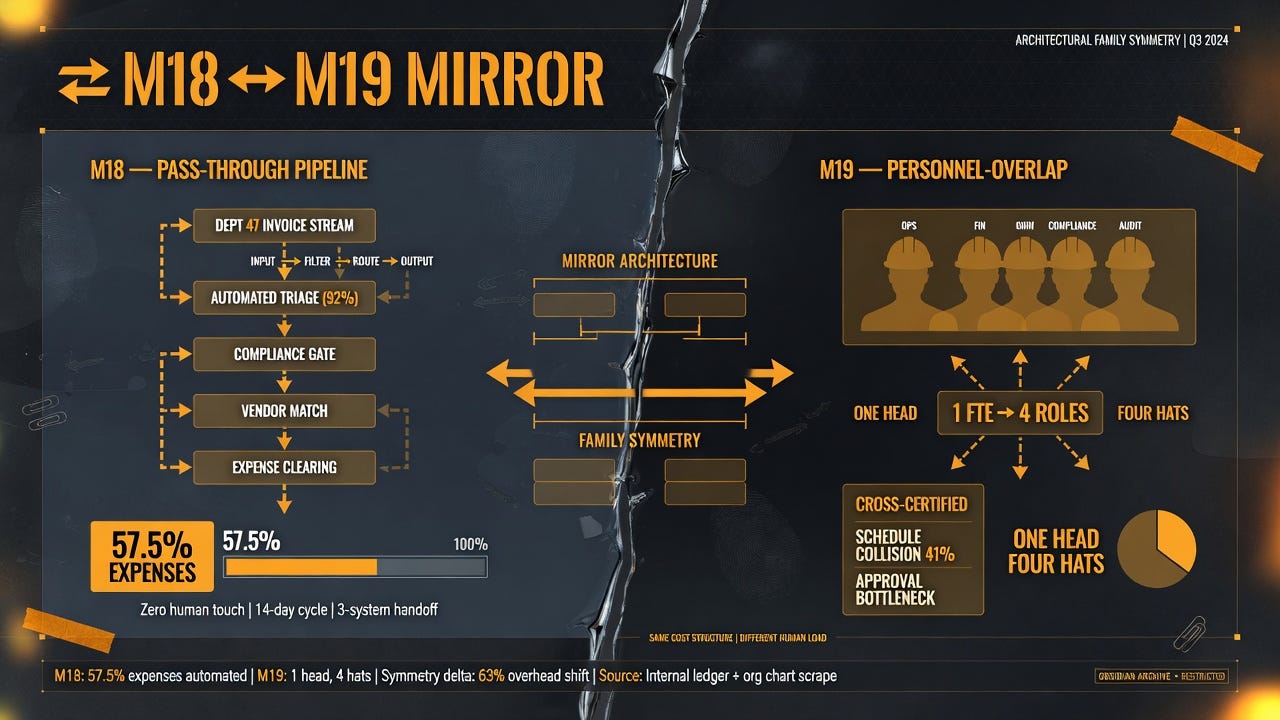
The architecture is legal under current rules. That is the firewall’s load-bearing fact. The firewall does not depend on the architecture being illegal or partisan or aligned. The firewall depends on the architecture being structurally identical across positions a reader would otherwise read as opposite.
The reader who arrived expecting an exposé of one foreign principal can leave with an understanding of an architectural class. The reader who arrived expecting a partisan exposé can leave with the same.
VI. The Tools Frame
This is a tool. Tools don’t pick sides. The side that shows up owns the tool. If you don’t show up, somebody else will — and they may not have your town in mind. Will they have the safety of your children in mind?
VII. What You Can Do This Week
This week’s Citizen Action Card walks five steps a reader can run, in about ten minutes, on any 501(c)(3) registered in the United States. The case study in this article is one US nonprofit network with overlapping officer roles across four legal entities at one address. The same five steps, run on a nonprofit incorporated in your county, will tell you the same kinds of things — and surface the same kinds of patterns, when those patterns exist.
The skill is portable. The case study is the demonstration. The local case is the actual reason to learn it.
Pull the card. Pull a 990. Walk the five steps on the case-study network — see the architecture name itself in plain English. Then pull a Form 990 for a tax-exempt organization in your zip code. Pull its Schedule R. Search the state business registry for its address. Count the officer overlaps.
Most of the time, the audit will show a clean, transparent, well-governed nonprofit doing exactly what it says it does. That is itself worth knowing. Trust earned by audit is more durable than trust given by default. The skill exists either way.
You will know more about the legal architecture of one nonprofit in your town than ninety-five percent of the people who live in your town. That is not a small thing. That is the beginning of the audit lane this series exists to open.
MODULE 19: CIVIC ACTION CARD
Public Sources Cited
ProPublica Nonprofit Explorer — projects.propublica.org/nonprofits — primary public-facing 990 access. Entity One EIN eight seven, zero nine nine four five eight six. Entity Two EIN eight seven, four zero zero seven five zero seven.
IRS Tax Exempt Organization Search (TEOS) — apps.irs.gov/app/eos/ — confirmation of tax-exempt status and the public auto-revocation list. Entity Two appears on the auto-revocation list with revocation effective May twenty twenty-four.
Florida Sunbiz — sunbiz.org — Florida Secretary of State corporate registry. Entity Two principal record. Entity Three principal record.
Georgia Corporations — ecorp.sos.ga.gov — Georgia Secretary of State corporate registry. Entity One operational-HQ filings. Entity Three filings.
IRS Form 990-N (e-Postcard) — IRC § 6033 and Revenue Procedure 2011-15 — the statutory and procedural framework for the e-Postcard filing classification, including the fifty-thousand-dollar gross-receipts threshold and the three-consecutive-years auto-revocation rule.
FEC Coordination Rules — 11 C F R § 109.20 and following — statutory framework for what does and does not constitute coordination between candidate committees and independent spenders.
Foreign Agents Registration Act, 22 U S C § 611 and following — for the directional-control element of the FARA framework as walked in Module 18.
Court Records (Active Litigation, Referenced Where Public) — L-Strategies v. Conz, Meriwether County, Georgia. Murphy v. Lemets, Sarasota, Florida. Both cases are publicly filed civil matters. The article references the cases only by their docket names and only at the level of public filing. All allegations in either case remain allegations until adjudicated.
The organization’s own public materials — Entity One’s website, press releases on EIN Presswire, and publicly archived versions thereof — for the organization’s self-described scope, leadership, and operations.
Related Series Reading
Module 18 — The Box In The Middle — the paired-mirror module on the foreign-aligned pass-through mechanism. The first half of the cross-border firewall this article closes.
Module 16 — The Engine That Looks Like Seven Engines — the domestic blue-coat half of the Big Players quartet. Walks the management-firm-as-passthrough architecture at scale.
Module 17 — The One Point Six Billion Dollar Donation You Never Voted On — the domestic red-coat half. Walks the trust-and-cascade architecture at scale.
Module 9 — Personnel Overlap Coordination — the original mechanism module on the personnel-concentration mechanism. Module 19 is Module 9’s argument at one specific case study’s scale.
Module 20 — AFPI Shell (dropping next) — the next module in Part Four. Walks a different shell-network application of the same architectural family. Continues the Inevitability Argument.
Module 7 — Delaware LLC Opacity — the LLC-specific opacity module. M19’s LLC components inherit the architecture Module 7 walked.
This article is the fourth deliverable in Part Four — The Big Players — of the Shadow Patriots civic-research series. It is the second half of a paired drop with Module 18 on the foreign-alignment axis after Modules 16 and 17 established the domestic axis. The pairing is the cross-border firewall doctrine of this series.
Editorial discipline (Two-Tier Naming Doctrine, locked 2026-04-24): Module 19 operates under Tier 2 Information Operations doctrine. Named legal entities are permitted at receipts level inside the article body because the entity names are the load-bearing public-record citations. Individual officers of those entities are not named by surname in the article body, headline, subhead, social-media copy, or thumbnail. The nation-state alignment of the network’s foreign principal is not asserted in title, subtitle, marketing copy, or chapter labels. The architecture is the subject.
Evidence standard: every factual claim in this article is verifiable through publicly filed Form 990s, the IRS auto-revocation list, the Florida and Georgia Secretary of State business registries, the FEC coordination rules, the FARA registry, the organization’s own public materials, and publicly filed civil court records cited only at the docket-name and procedural level. PMC alleges no criminality, no FEC violation, no FARA violation, no IRS violation, and no wrongdoing by any individual or organization named or unnamed. PMC describes the architecture in which twenty twenty-six citizens live and equips citizens with the literacy to identify the architecture themselves.
Subliminal through-line (Series Bible §0): every Citizen Action Card in this series teaches a transferable skill the reader can apply to a tax-exempt organization in the reader’s own town. The skill is the product. The architecture is the diagnosis. The citizen is the destination.
Active-litigation hedges: references to L-Strategies v. Conz (Meriwether County, Georgia) and Murphy v. Lemets (Sarasota, Florida) appear only at the public-docket level. All allegations in those matters remain allegations until adjudicated by a competent legal authority. PMC has reviewed the pre-publication template with legal counsel.
If you enjoyed this work and feel encouraged by independent investigations like this, please consider becoming a paid subscriber to 17sog.substack.com here on Substack, or donate at Project Milk Carton Inc. or at https://t.co/PvtnrODkNz
Your support helps us turn information into action for children and families by:
keeping high-risk and missing children visible
identifying gaps in the systems responsible for protecting them
giving families and communities clear, usable information they can act on
supporting education, outreach, and practical community-based solutions
maintaining the public-data and OSINT work that makes this accountability possible
building tools and resources designed to help communities protect children before they disappear into a system
Most importantly, please share this article.
Independent journalism survives when ordinary people help spread information.
And informed communities protect children.
ALL paid subscriptions are 100% tax deductible
Project Milk Carton | 501(c)(3) | EIN: 33-1323547