

From the PMC Research and Education Desk · Project Milk Carton · Module 6 of “The Game You Were Never Taught” · Financial Move 4 of 8
The move
This is the fourth of eight financial moves we will map in this series.
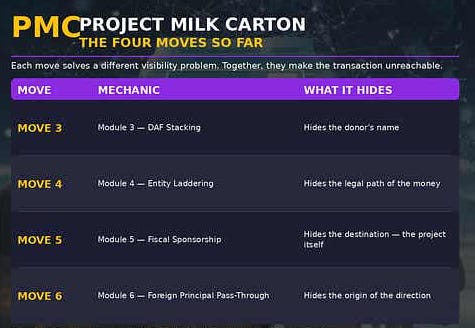
Module 3 — DAF Stacking — showed you how a donor-advised fund erases the donor’s name from a single donation.
Module 4 — Entity Laddering — showed you how a stack of legally separate organizations changes the legal identity of the money at every rung.
Module 5 — Fiscal Sponsorship — showed you how an advocacy project can operate inside a 501(c)(3) wrapper without ever becoming a legal entity at all.
Module 6 takes the mechanism international. It shows you how a foreign organization — a foreign government, a foreign state-owned entity, or a foreign political organization — can reach an American audience, fund a U.S. messaging operation, or seed a U.S. political narrative while avoiding the two disclosure regimes specifically designed to catch that activity: the Foreign Agents Registration Act (FARA, 22 U.S.C. § 611 et seq.) and the Federal Election Campaign Act (52 U.S.C. § 30101 et seq., including the 52 U.S.C. § 30121 foreign-national contribution prohibition).
The mechanism is called Foreign Principal Pass-Through. We call it The Slip — because the whole move is about how a foreign principal slips its reporting obligation by using a U.S. charity as a receiving station.
This is the neutralizer module. The same mechanic appears on both sides of American politics, with foreign principals in different directions. We are going to show you both in the same article, paid for by donors on both coasts, routed through nonprofits with opposite coded politics. The mechanism is the story. Not the party.
How it works — in plain English
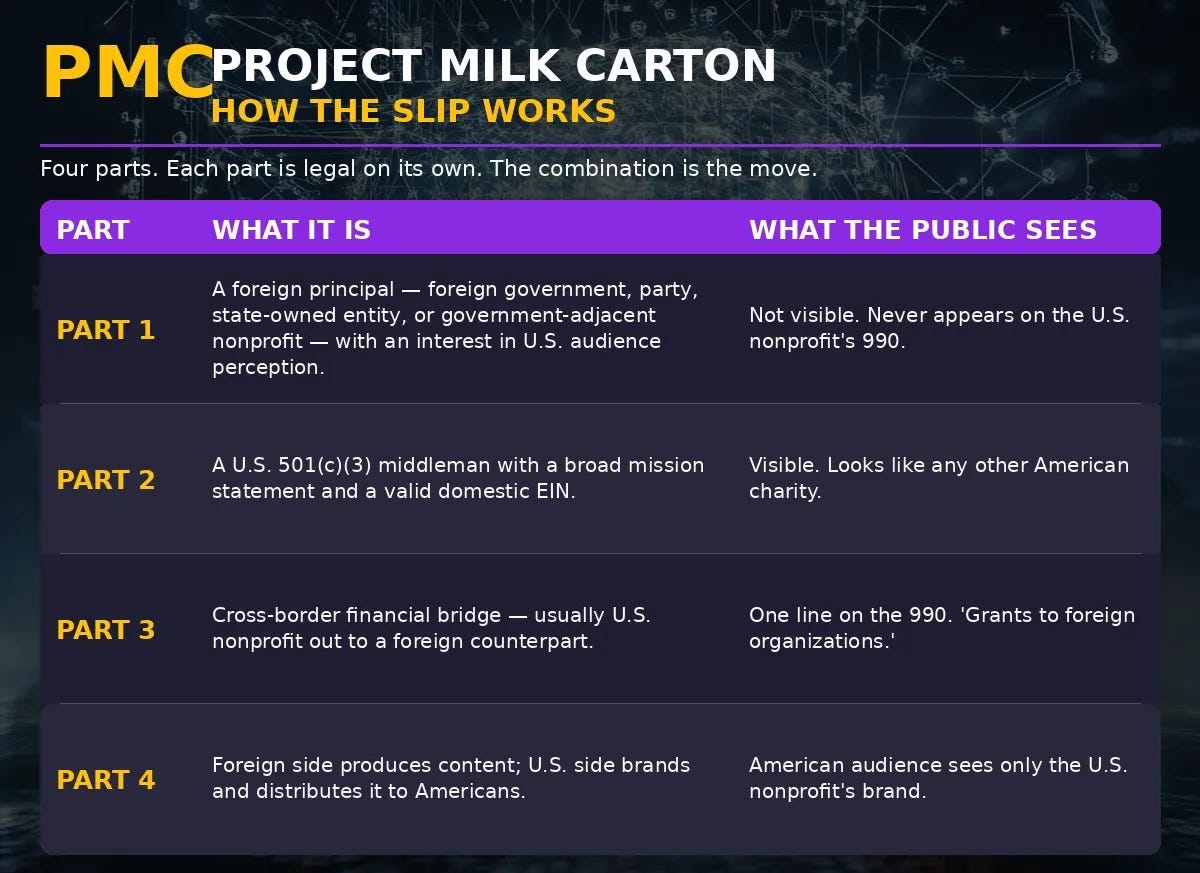
A foreign-principal pass-through has four parts.
Part 1 — The foreign principal. A foreign government, foreign political party, foreign state-owned entity, foreign-government-adjacent nonprofit, or a foreign national with a defined political objective. Under FARA this is any “foreign principal” as defined at 22 U.S.C. § 611(b). Under FECA, this is a “foreign national” at 52 U.S.C. § 30121(b). The foreign principal has an interest in what Americans believe, how Americans vote, or who Americans elect.
Part 2 — The U.S. 501(c)(3) middleman. A U.S.-registered 501(c)(3) nonprofit that has tax-exempt status, an EIN, a board, and a 990. On paper, the nonprofit is purely domestic. It is “educational,” or “charitable,” or a “public-interest research” organization. Its stated mission is broad enough to accommodate a wide range of content-production activity. Its public profile is American.
Part 3 — The financial bridge. A recurring transfer of money from the U.S. nonprofit to a foreign entity — often a foreign nonprofit “association” that is the operational counterpart of the U.S. entity. Or, running in the other direction, funds entering the U.S. nonprofit from foreign-linked donors and then being deployed domestically. Either way, the bridge is a line on a 990: “grants to foreign organizations,” or “program-service expenses for foreign operations,” or “advertising and consulting.” A single line. No foreign-principal disclosure. No FARA filing.
Part 4 — The deployment. The foreign-side operation produces content — research briefs, media monitoring reports, opposition files, narrative analyses — and feeds them back into the U.S. information environment under the U.S. nonprofit’s American brand. Or, in the reverse flow, a foreign-national-funded campaign operates domestically under a domestic nonprofit wrapper.
That is the full mechanic. Now the consequences.
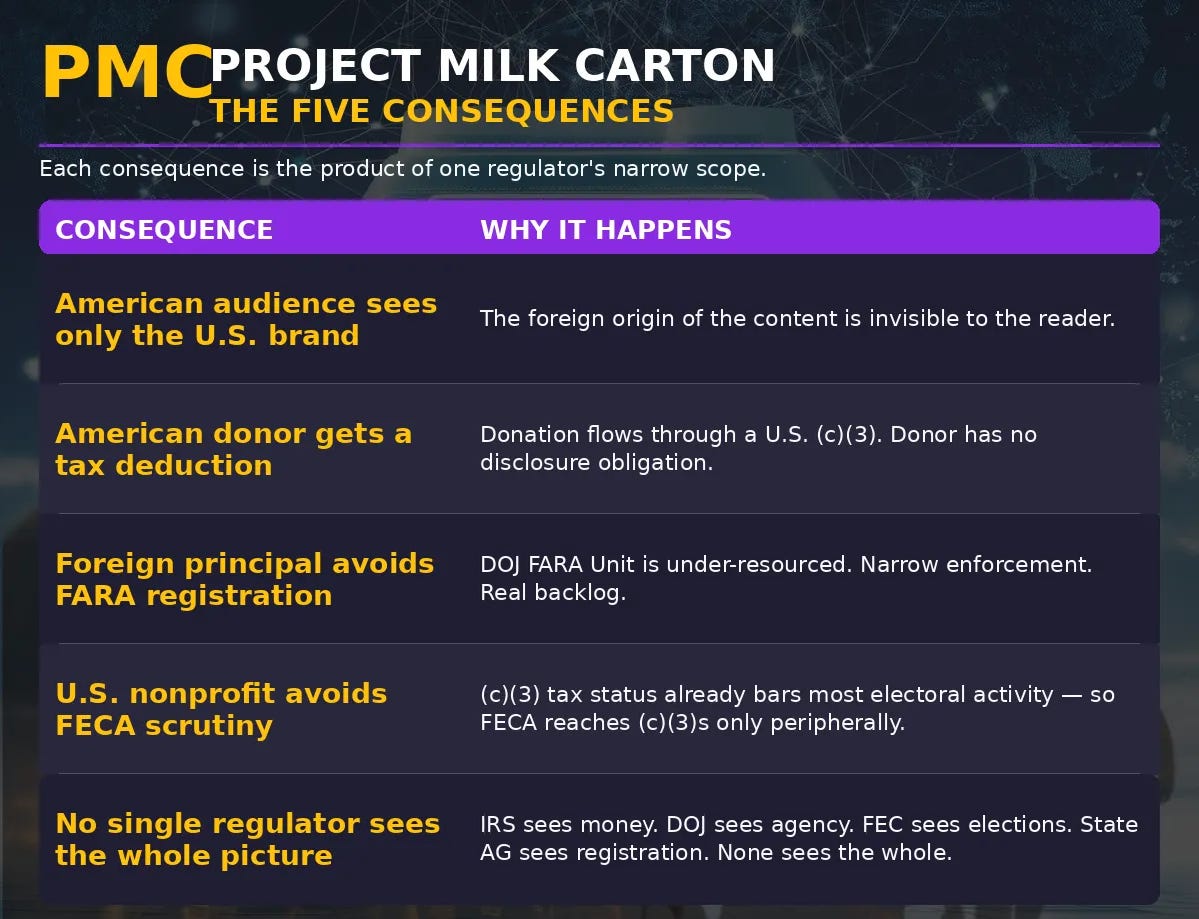
Consequence 1. A U.S. media audience receiving the foreign-produced content sees a domestic nonprofit’s brand, not the foreign principal. The origin is invisible to the reader, listener, or viewer.
Consequence 2. A donor to the U.S. nonprofit — including a tax-deductible donor — is legally donating to an American 501(c)(3). The donor’s gift is deductible. The donor has no disclosure obligation. The fact that the majority of the nonprofit’s spending supports a foreign entity is buried in aggregate expense categories on the 990.
Consequence 3. The foreign principal avoids FARA registration. FARA requires registration by any person acting as an agent of a foreign principal who engages in political activities, public relations, or fundraising in the United States. But the Department of Justice’s FARA Unit has limited enforcement resources, a narrow interpretation of “agency,” and a backlog of referrals. A U.S. 501(c)(3) that denies it is acting on behalf of a foreign principal — even when most of its budget flows to a foreign counterpart — can operate unregistered for years.
Consequence 4. The U.S. nonprofit avoids FECA foreign-national-contribution scrutiny. FECA § 30121 bars foreign nationals from making contributions or expenditures in connection with any federal, state, or local election. A (c)(3) is barred by its own tax status from partisan electoral intervention, which technically keeps foreign-funded (c)(3)s out of FECA reach — even when the (c)(3)’s non-electoral content production (media monitoring, opposition research, “educational” messaging) materially shapes election-cycle narratives.
Consequence 5. The IRS does not adjudicate FARA. The Department of Justice does. The state attorneys general who oversee charitable registration do not adjudicate FARA. The Federal Election Commission does not adjudicate FARA. No single regulator holds the full picture. The foreign-principal pass-through lives in the seam between three regulators, none of whom can close it alone.
This is The Slip. A foreign principal reaches an American audience through a U.S. charity that is legally not a foreign agent, financially not a foreign donor, and politically not a foreign-election-interfering entity — even when, functionally, it is acting for all three.
The scale
Foreign-principal pass-through is legal where it is not prosecuted. It is common where it is legal. And it is massive where it is common.
Most 990-filing U.S. charities with foreign-operational activity file a Schedule F — an annex to the 990 that discloses foreign grants, foreign programs, and foreign activities. Schedule F is itself an important transparency document. But Schedule F discloses grants to foreign organizations. It does not disclose when the foreign organization is the principal — the entity whose direction or content is driving the U.S. nonprofit’s program activity.
FARA, which is the statute that does address principal-agent foreign direction, has been enforced episodically and with uneven scope since its enactment in 1938. The Department of Justice National Security Division’s FARA Unit handles the full enforcement docket. In recent years the FARA Unit has expanded its advisory-opinion program, issued more public guidance, and pursued a small number of high-profile unregistered-agent prosecutions. The Unit remains under-resourced relative to the scale of potentially covered activity — by the Unit’s own 2022 public communications, by Government Accountability Office reviews, and by independent academic analysis.
The pass-through move exploits this enforcement gap. It is not exotic. It is infrastructure.
Why this is the fourth move
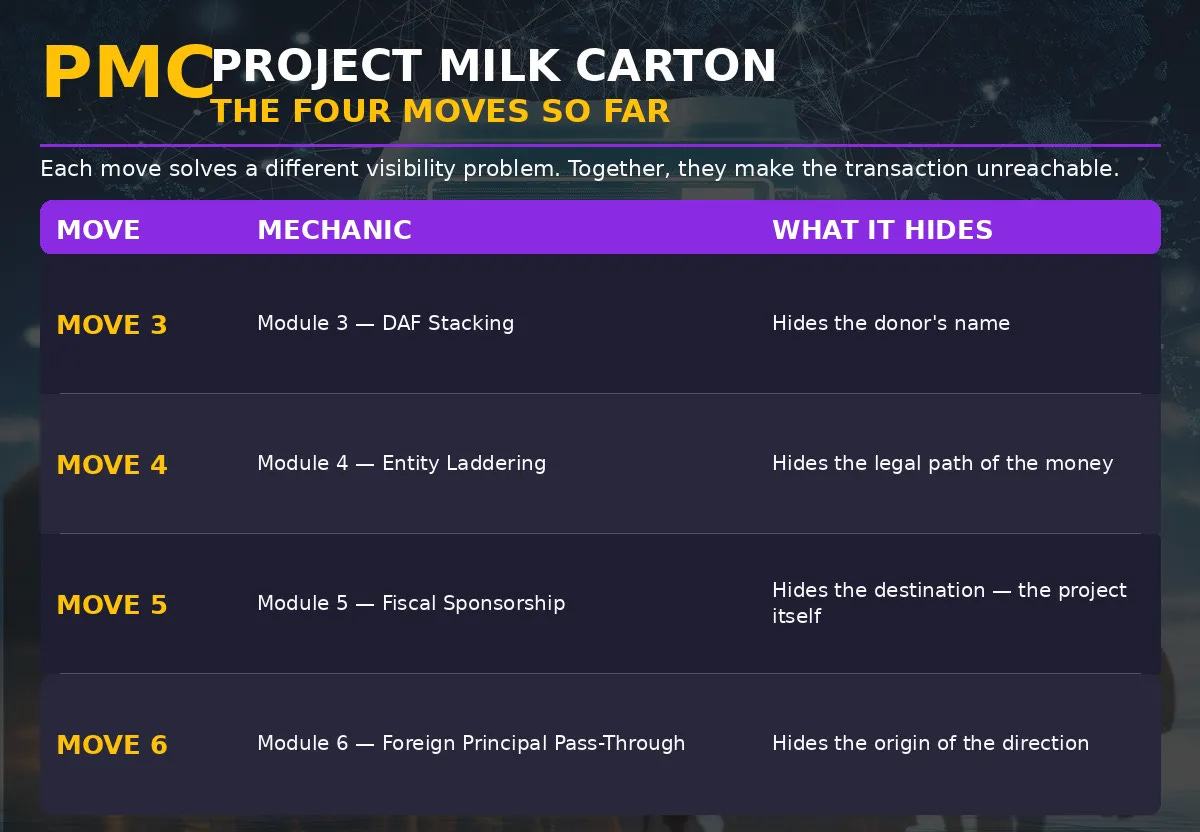
Move 1 — DAF Stacking — hid the donor’s name.
Move 2 — Entity Laddering — hid the legal path of the money.
Move 3 — Fiscal Sponsorship — hid the destination of the money.
Move 4 — Foreign Principal Pass-Through — hides the origin of the direction. A U.S. audience receiving the output cannot see that a foreign entity is steering the content, the target selection, or the editorial framing. The financial flow documents the relationship. The disclosure regime does not capture it.
Each move solves a different visibility problem. Together they make the transaction invisible, then untraceable, then unattributable, then unreachable. By the end of Move 4, a foreign government can reach a U.S. audience — millions of Americans — through a pipeline that uses a charity the U.S. public trusts as a credibility screen.
Subsequent moves in the series — Delaware LLC opacity, “educational” classification abuse — extend The Slip in specific directions. Foreign Principal Pass-Through is the structural move that opens the American information environment to offshore direction without formal foreign-principal registration.
There are legitimate uses

Foreign-operational U.S. charities exist for entirely legitimate reasons. A U.S.-based international-development nonprofit that builds clean-water systems in East Africa files Schedule F because it has foreign operations — that is what Schedule F is for. A U.S. disaster-relief charity that ships supplies to Turkey after an earthquake files Schedule F. A U.S. academic exchange program that hosts foreign students files the corresponding disclosures. These are clean, appropriate uses.
The technique becomes a problem only when the direction is foreign. When the U.S. nonprofit is not running an American charitable mission that happens to have foreign operations, but is instead receiving foreign editorial direction, foreign-produced content, or foreign operational objectives and deploying them under an American brand — that is The Slip. The distinguishing signals are specific:
Majority foreign expense share. A U.S. 501(c)(3) routing more than half of its annual expenses to a single foreign entity — especially a foreign nonprofit association, foreign political party, or foreign-government-adjacent nonprofit — is running its program through the foreign counterpart, not the other way around.
Governance overlap with a foreign government. Officers, board members, or senior advisors with concurrent or recent service in a foreign government, foreign-government-funded program, or foreign-government-endorsed institution indicate that the U.S. nonprofit is operationally close to foreign-state interests.
Content pipeline. The U.S. nonprofit’s principal deliverables — research products, media analysis, narrative assessments, targeting profiles — are produced by or primarily for the foreign entity, then branded as the U.S. nonprofit’s work for American release.
Asymmetric revenue. The U.S. nonprofit raises money in the United States, issues U.S. tax receipts, and deploys the money abroad to the foreign counterpart. The American donor pool is the funding mechanism; the foreign entity is the operational beneficiary.
Anonymized inbound funding. A substantial share of the U.S. nonprofit’s revenue originates through donor-advised funds (Module 3), private foundations, or anonymous donor vehicles — keeping both the donor identities and the donor alignments out of the public record.
No FARA filing. The U.S. nonprofit has not registered under FARA, has not sought a FARA advisory opinion, and does not identify itself publicly as acting for a foreign principal — even where the financial and personnel indicators are present.
All six signals together define the pattern. Any two or three should prompt a closer look. Four or five is the profile of a pass-through running on autopilot.
Case Study A — The Gun-Rights Backchannel

Sources: federal court records, and published reporting from NPR, The Hill, and other national outlets.
The red-coded case is the rare pass-through with a courtroom ending, which is what makes it worth studying: it shows what the pattern looks like when the Department of Justice proves it.
Between 2015 and 2017, a Russian national named Maria Butina built relationships inside American conservative and gun-rights circles, most visibly around the National Rifle Association, presenting herself as a gun-rights activist and graduate student. According to federal prosecutors, she was working under the direction of Alexander Torshin, a senior official of the Russian central bank, to build unofficial channels between Russian officials and influential Americans, and to report what she learned back to Moscow. The vehicle was not an embassy or a lobbying firm. It was the trusted social infrastructure of American civil society: conventions, prayer breakfasts, nonprofit gatherings, and the credibility that comes from moving inside them.
In December 2018 Butina pleaded guilty to conspiring to act as an unregistered agent of a foreign government, and in April 2019 a federal judge sentenced her to 18 months, saying the conduct was sophisticated and “penetrated deep into U.S. political organizations.” She was deported to Russia after serving her sentence. The organizations she moved through were not charged with anything; the NRA said its leadership had not sanctioned the Moscow trip that figured in the case. Butina maintained she was trying to improve relations between the two countries.
This case is coded red because the audience the operation cultivated was conservative-coded. Notice what it proves about the mechanism: the foreign principal did not need to own a nonprofit. Access to the trust inside one ecosystem was enough, and the only reason the public knows is that this one, unusually, was prosecuted.
Case Study B — The Shanghai Funder’s Network

The structure. Veterans for America First (VFAF) was founded in 2015 as a veterans-aligned political organization. Its public-facing operations have run under multiple domains, consolidated in 2024 onto the domain vfaf.us, hosted on U.S.-based commercial cloud infrastructure (Oracle Cloud, Phoenix, Arizona; IBM Cloud mail infrastructure, Washington, D.C.). The organization’s public-entity stack includes a 501(c) nonprofit, an affiliated political action committee, and one or more adjacent consulting LLCs.
The documented foreign-nexus event. In March 2019, a VFAF-branded Facebook page with more than 100,000 followers was documentedly hijacked by a North Macedonian businessman identified in public reporting as Panche “Pane” Arsov. The hijacking is documented in reporting by the Washington Post (September 17, 2019), in Congressional testimony before the House Committee on Veterans’ Affairs (“Hijacking Our Heroes” hearing, H. Rept. 116-657, November 13, 2019), and in investigative reporting by OCCRP, IRL.mk, and BuzzFeed News. The Macedonian operators are, according to that reporting, part of the Veles-based pro-Trump fake-news ecosystem that was separately documented around the 2016 U.S. election cycle. During the period of Macedonian control of the Facebook page, the page shared anti-Democrat content and solicited donations via PayPal linked to a North Macedonian website.
The event is a confirmed, publicly documented, foreign-nexus compromise of a U.S. veterans-branded political operation’s distribution infrastructure. It is not an infrastructure-compromise event. VFAF’s own hosting and email infrastructure is, and was, U.S.-based.
The structural observation. The VFAF ecosystem combines (a) a 501(c) nonprofit, (b) a PAC, and (c) consulting LLCs in a stack of the form Modules 3, 4, and 5 of this series have already mapped: donor-advised-fund inbound revenue; entity-laddered legal identity; fiscally-adjacent program activity inside the (c)(3); and distribution through a social-media audience that was, at one documented point, compromised by foreign operators. The personnel nexus includes individuals with publicly documented Russian-language-region backgrounds and real-estate, legal-services, and consulting activity across Florida, Georgia, and Virginia.
What this Case Study establishes. VFAF is not, on the current publicly available record, an adjudicated foreign-principal pass-through in the statutory FARA sense. What it is — and what is relevant to this module — is a documented example of a veterans-branded U.S. political operation whose distribution infrastructure was foreign-compromised, whose entity-stack exhibits the same structural pattern as Case A, and whose personnel network has publicly documented foreign-nexus signals that the Department of Justice, the IRS, the Federal Election Commission, and state attorneys general are each partly positioned to adjudicate, and none positioned to adjudicate fully.
Coding. Case B is coded red-adjacent by public perception — VFAF’s branding and audience are conservative-coded. The foreign nexus in Case B runs in a different direction than in Case A. Case A’s foreign counterpart is Israeli. Case B’s foreign-compromise event involved North Macedonian operators, with separate and unresolved questions about Russian-language-region personnel nexus. Two different foreign principals. Two different directions. Same structural pattern. Different coded American audiences. The mechanic is non-partisan. That is the point of this module.
The legal architecture
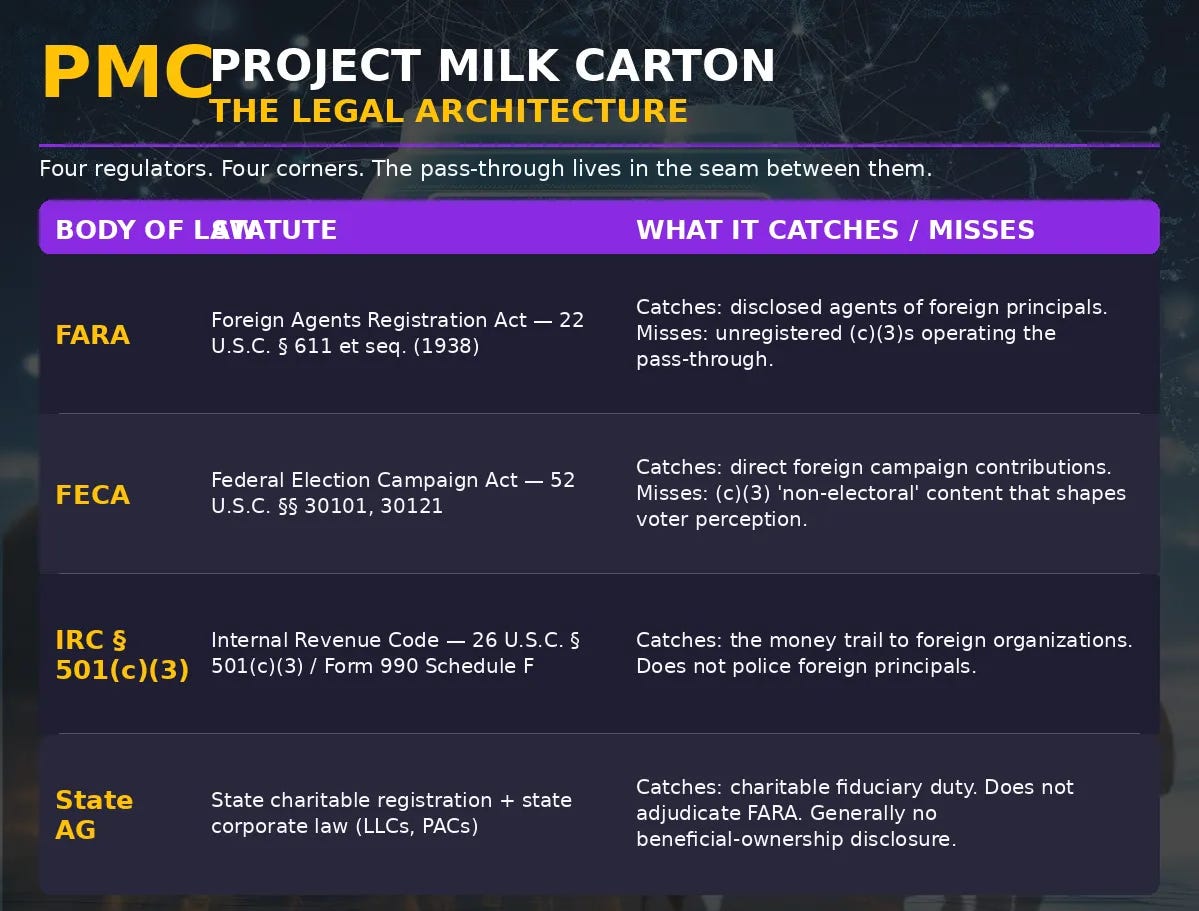
Four bodies of law combine to make foreign-principal pass-through legal where it is not prosecuted, and hard to prosecute where it is illegal.
The Foreign Agents Registration Act (FARA). 22 U.S.C. § 611 et seq. Enacted in 1938 to address foreign-government propaganda in the United States in the run-up to World War II. FARA requires registration by any “agent of a foreign principal” who engages in “political activities,” “public relations counsel,” “information-service employee” activity, or “political consulting” in the United States on behalf of that foreign principal. Registration requires full disclosure of the agency relationship, the activities conducted, and the financial flows. Violations carry civil and criminal penalties. In practice, FARA enforcement has been episodic, narrowly scoped, and concentrated on a small number of high-profile cases. The Department of Justice’s FARA Unit — the exclusive federal enforcer — remains under-resourced relative to the scale of potentially covered activity.
The Federal Election Campaign Act (FECA). 52 U.S.C. § 30101 et seq., with the foreign-national contribution prohibition at 52 U.S.C. § 30121. FECA bars foreign nationals from making contributions or expenditures “in connection with” any federal, state, or local election. FECA is enforced by the Federal Election Commission (civil) and the Department of Justice (criminal). 501(c)(3) organizations are barred by their own tax status from most electoral intervention, so FECA reaches them only peripherally — even when their non-electoral activity (media monitoring, research briefs, narrative analysis) shapes election-cycle discourse.
The Internal Revenue Code. 26 U.S.C. § 501(c)(3), with foreign-operations disclosure at IRS Form 990 Schedule F. The IRC permits a U.S. 501(c)(3) to operate abroad, grant to foreign organizations, and receive donor-deductible contributions that fund foreign activities — as long as the charitable purpose is maintained and Schedule F is filed. The IRC does not police foreign principals. The Department of Justice does.
State charitable registration and corporate law. Each state’s attorney general is empowered to oversee charitable solicitations in that state and to adjudicate fiduciary compliance by nonprofits registered to operate there. State AGs do not adjudicate FARA. State corporate law governs the LLCs and PACs that typically adjoin the 501(c)(3) in the pass-through stack; state corporate law generally does not require beneficial-ownership disclosure of LLCs unless (as Module 7 will cover) FinCEN’s Beneficial Ownership Information reporting applies.
The architecture was never designed to be closed. It was designed to be partitioned — on the assumption that four regulators could each handle their corner of the problem. In practice, the foreign-principal pass-through lives in the seam between all four. The IRS sees the money. The DOJ FARA Unit sees the agency relationship. The FEC sees the electoral impact. The state AG sees the charitable registration. No single regulator sees the whole thing.
Reformers have proposed legislation that would require 501(c)(3) organizations with more than a de minimis level of foreign-principal-aligned activity to file a FARA advisory opinion request or a disclosure attestation. As of this writing, no such requirement has become law.
What you can do
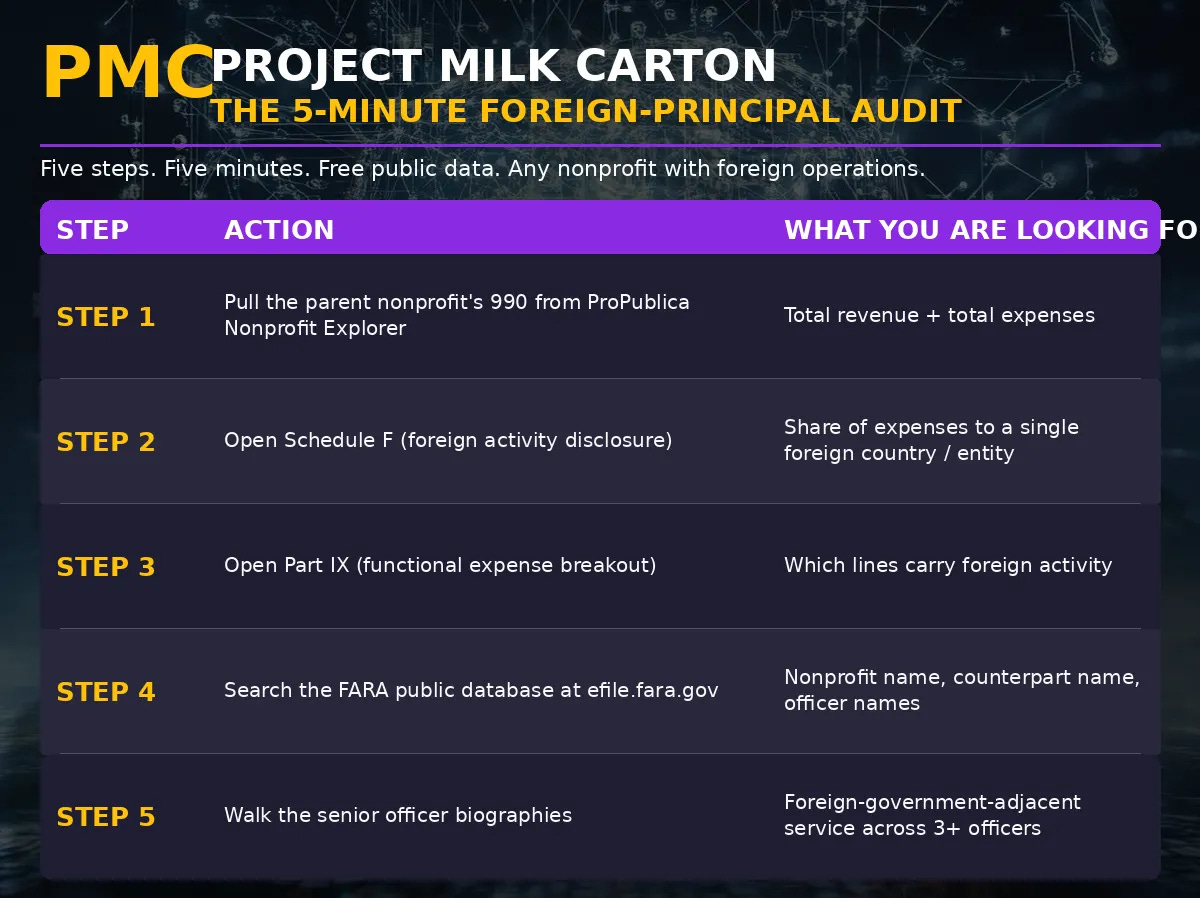
This is where the citizen action card that accompanies this article teaches you the five-minute foreign-principal audit — how to take any U.S. 501(c)(3) with a foreign operational footprint, pull its 990 from the ProPublica Nonprofit Explorer, and use three specific schedules to estimate the likelihood that the organization is operating as an unregistered foreign-principal agent.
The specific techniques you will learn include:
Schedule F analysis. The 990’s Schedule F lists grants and activities outside the United States. A single-country concentration of foreign-grant activity, especially to a single foreign “organization” that is not itself a widely recognized humanitarian or development entity, is the first signal.
Part IX analysis. Part IX breaks out functional expenses. If more than a third of program expenses are routed through “grants to foreign organizations,” the entity’s program is substantially foreign.
FARA database check. The Department of Justice maintains a public FARA database at efile.fara.gov. Every registered agent is searchable. Searching by name of the U.S. nonprofit, the name of the foreign counterpart, and the names of the senior officers will either confirm a FARA filing or confirm its absence.
Schedule B caveat. IRS Form 990 Schedule B identifies large donors to the organization, but IRS rules redact donor identities on the publicly disclosed version of Schedule B for 501(c)(3) organizations. This is the Schedule B black hole — the subject of Module 10 of this series. Module 6 notes the gap; Module 10 unpacks it.
Officer biography walk. Each senior officer’s public biography, LinkedIn profile, and published interviews should be reviewed for concurrent or recent service in a foreign government, foreign-government-endorsed institution, or foreign-state-adjacent program. A cluster of such service among three or more senior officers is a governance-overlap signal.
By Module 8, you will be able to look at any politically active U.S. nonprofit — red, blue, foreign, domestic — and read its foreign-principal profile in under two minutes.
Module 6: Citizen Action Card, Catch the Slip
The next move

Module 7 will cover Delaware LLC Opacity — how the Delaware limited-liability-company structure, combined with the March 2025 FinCEN Beneficial Ownership Information reporting exemption for certain domestic entities, produces U.S. shell entities whose beneficial owners are effectively untraceable by U.S. regulators.
Move 4 exposed how foreign direction reaches a U.S. audience through a charitable wrapper. Move 5 will show you how the shell entity at the end of the wrapper can itself be rendered opaque to U.S. law.
We will map it the same way: mechanism, scale, red case, blue case, citizen action card.
Run the audit. If you find something that deserves a second set of eyes, send it to us through projectmilkcarton.org.
Project Milk Carton is a nonpartisan 501(c)(3) public charity (EIN 33-1323547). Case Study A draws on federal court records and national press reporting. Case Study B draws on published reporting and official congressional records; it describes pending inquiries, and the organizations involved deny wrongdoing and are presumed to have violated no law unless a competent authority ever finds otherwise.
Read the series: M0 “The Game You Were Never Taught” · M1 “The Tax Code That Became a Battlefield” · M2 “Reading the Map: Decoded” · M3 “The Anonymous Donor” · M4 “The Russian Doll” · M5 “The Backpack Trick” · Visit projectmilkcarton.org
Sources
Federal Election Campaign Act foreign-national prohibition, 52 U.S.C. § 30121
Department of Justice FARA Unit and public registration database
ProPublica Nonprofit Explorer: the public IRS filings, including Schedule F, for U.S. charities with foreign operations
NPR: the December 2018 guilty plea in the foreign-agent conspiracy case
House Ways and Means Committee: records demand to a Singham-funded nonprofit, September 2025
Congressional Research Service: reports on FARA and campaign finance law