


Module 7 showed you how a Delaware LLC becomes a corporate ghost — a legal person whose owner is unknown on the public record, by design. You learned to read the opacity profile of an entity whose function was anonymity.
Module 8 is the companion problem, and in some ways the more dangerous one. Because where the Delaware LLC hides the owner, the “educational” 501(c)(3) hides the purpose.
A political operation classified as “educational” under section 501(c)(3) of the Internal Revenue Code is not obligated to disclose its donors to the public, pays no federal income tax on program revenue, can receive gifts that the donor deducts from personal income, accepts grants from other 501(c)(3)s under the “private foundation” rules, and is legally presumed to be acting in the public interest.
The classification itself is the credential. Once it is in place, the IRS does not review whether the content actually teaches anything. No federal regulator reads the lesson plans. No state board audits the curriculum. The filing says “educational,” and the money moves accordingly.
This module teaches you how to read a 501(c)(3)’s filings against its programs, identify the tell-tale markers of educational classification abuse, and — in five minutes — audit whether a nonprofit’s “educational” mission is actually teaching, or is cover for something else.

Part I — The Two Rules That Were Supposed to Prevent This
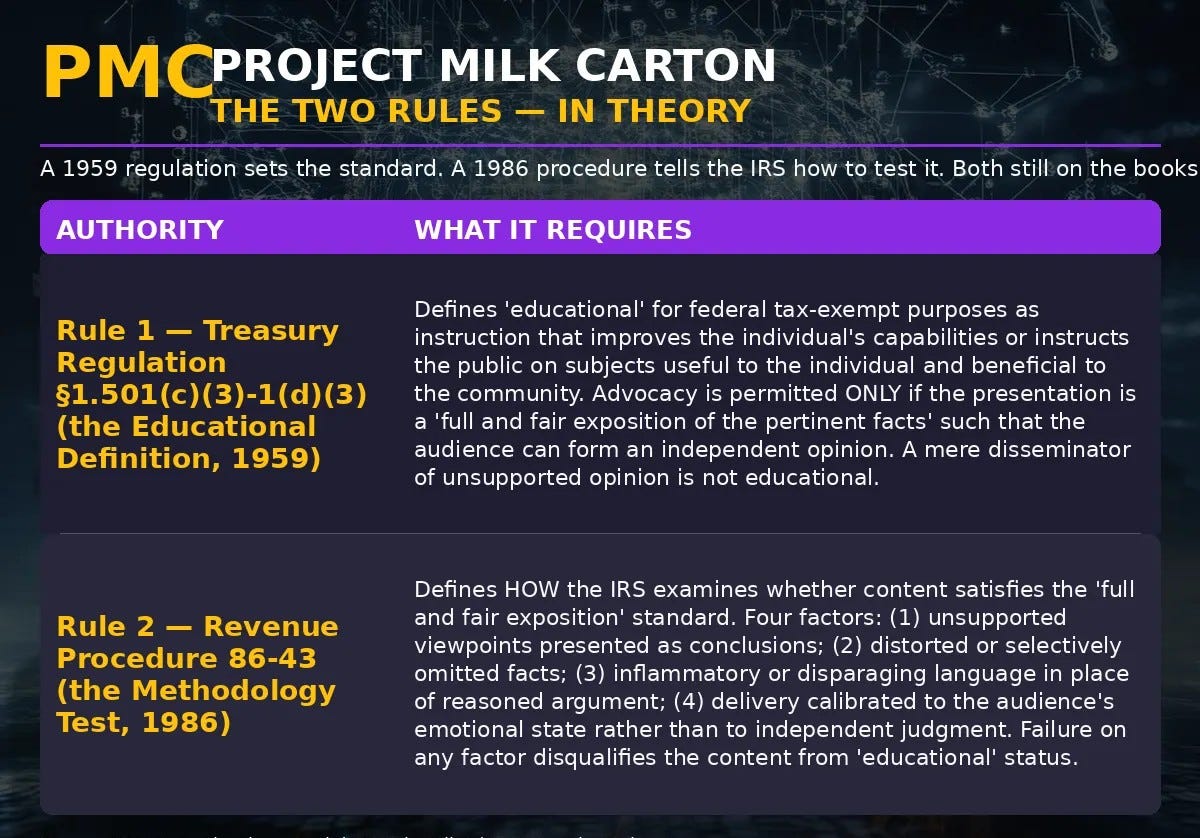
The “educational” classification under section 501(c)(3) is governed by two specific legal instruments. Both are public, both are binding, and both are — in practice — rarely enforced.
Rule 1: Treasury Regulation §1.501(c)(3)-1(d)(3) — The Educational Definition.
The regulation defines “educational” narrowly: the instruction of the individual for the purpose of improving or developing her capabilities, or the instruction of the public on subjects useful to the individual and beneficial to the community. The regulation explicitly states that “an organization may be educational even though it advocates a particular position or viewpoint so long as it presents a sufficiently full and fair exposition of the pertinent facts as to permit an individual or the public to form an independent opinion or conclusion.”
Read that sentence twice. The regulation does not prohibit advocacy. It permits advocacy inside educational programming — but only if the advocacy is paired with a full and fair exposition of the facts, such that the reader, viewer, or student can form an independent opinion.
Rule 2: Revenue Procedure 86-43 — The Methodology Test.
Because the regulation’s “full and fair exposition” language was, by itself, unenforceable, the IRS in 1986 issued Revenue Procedure 86-43. That procedure defines a four-factor Methodology Test the IRS agent is supposed to apply when reviewing an application for educational status — or, in theory, when auditing an organization’s educational activity.
The four factors:
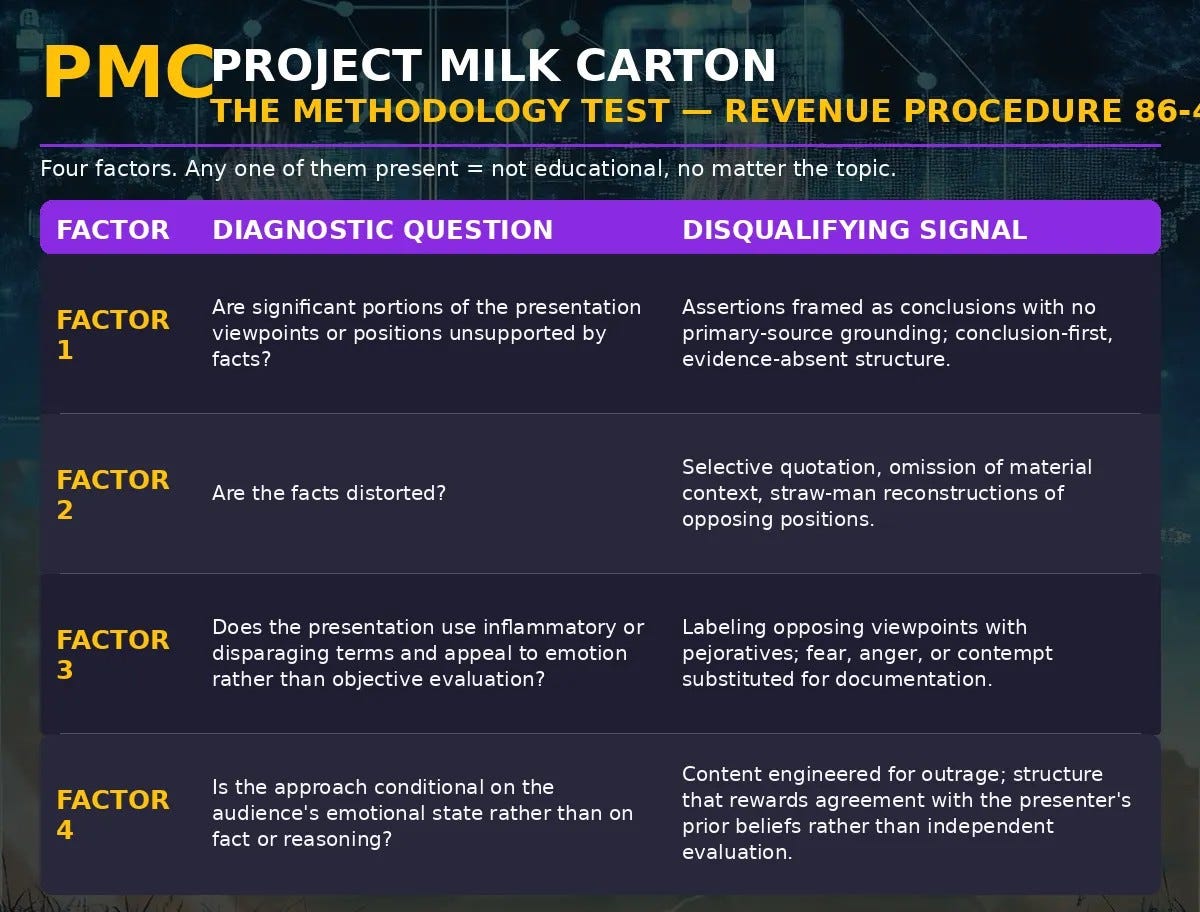
Are viewpoints unsupported by facts presented as substantial conclusions? If the organization presents a position as a conclusion without meaningful factual support, the activity is not educational.
Are facts distorted to make a point? If the presentation misrepresents, selectively omits, or misstates the factual record, the activity is not educational.
Are emotional appeals substituted for reasoned arguments? If the programming relies on inflammatory, disparaging, or emotionally charged language rather than reasoned presentation, the activity is not educational.
Is the approach calibrated to permit an informed opinion? If the method of presentation does not permit the audience to make a reasoned, independent judgment, the activity is not educational.
These two rules — the regulation and the Methodology Test — are the floor. That floor was established precisely because Congress foresaw that “educational” classification would be the obvious shell for political content, and wanted a test an IRS agent could apply.
Revocations of educational status on methodology grounds are vanishingly rare. The floor exists on paper. Enforcement seldom reaches it.
Part II — The Four-Part Mechanicrt Mechanic

The “educational” (c)(3) abuse pattern has four repeatable mechanics.
Step 1 — Apply for (c)(3) status under the educational exempt purpose.
Form 1023 asks the applicant to describe its exempt purpose. The applicant writes “educational” as the purpose category, and describes programs in general language: “to educate the public about,” “to provide educational resources on,” “to produce and distribute educational content regarding,” followed by a broad subject area.
The IRS reviews the application. The review is largely paper-based. The IRS agent reading the application has broad discretion but limited time, and “educational” applications with generic-sounding program descriptions are typically approved.
Step 2 — Write a broad mission statement.
The mission statement on the (c)(3)’s Form 990 and its bylaws is drafted in abstract, umbrella language. It does not commit to any specific methodology, any specific curriculum, any specific balance of perspectives. A typical pattern: “Our mission is to educate the American public about [broad subject area] and to provide educational resources to students, teachers, and policy makers.”
That sentence is compatible with genuine education. It is also compatible with pure advocacy. The mission statement does not distinguish between them.
Step 3 — Run programs that advocate while looking like curriculum.
The organization produces content. The content looks educational in format: lessons, videos, books, teacher guides, conference panels, fellowships. In substance, the content presents a predetermined viewpoint — typically aligned with a political movement, a partisan policy agenda, or a coordinated legislative effort — as the conclusion the audience is meant to reach.
If the Methodology Test were applied rigorously to that content, much of it would fail factor 1 (viewpoints as conclusions), factor 3 (emotional appeals), or factor 4 (reasoned independent judgment). The IRS does not apply the Methodology Test rigorously to content produced after the (c)(3) is approved. The determination is at the application stage; the content is at the operational stage; the two are rarely reconnected.
Step 4 — Use the (c)(3) status as a credential.
Once the classification is secured, it is used externally as proof of educational legitimacy. School districts approve the materials because the organization is a 501(c)(3). Employers match donations because the organization is a 501(c)(3). Foundation grants flow because the organization is a 501(c)(3). Donors deduct contributions because the organization is a 501(c)(3). Social media platforms grant “nonprofit” status in algorithmic amplification because the organization is a 501(c)(3).
The four-letter classification — (c)(3) — does the work of validating the content, even though the classification itself is silent about content.

Part III — What Each Regulator Can’t See
The educational classification abuse pattern works because of what the enforcement architecture does not do. Five specific disclosure gaps make the mechanic durable.
The IRS does not audit educational content post-approval. Once the (c)(3) is determined, the organization’s content is not subject to routine methodological review. The IRS Exempt Organizations function is a small office responsible for nearly two million organizations. Reading curricula at scale is not in the operating model.
State charity regulators do not review educational content. State AGs and charity registration authorities review financial compliance, fraud, and solicitation practices — not curriculum. Whether an educational (c)(3) is actually educating is not in their statutory lane.
Donors receive the same deduction whether the content is neutral or partisan. The federal tax deduction for a (c)(3) gift does not depend on content. A donor who contributes $10,000 to a genuine educational research institute and a donor who contributes $10,000 to a partisan advocacy operation wearing an educational label receive the same deduction.
Employer matching programs rely on the IRS classification, not the content. Corporate matching-gift programs use IRS Publication 78 as the authoritative list. An employee can direct a matched donation to a politically aligned “educational” (c)(3) and have the employer unknowingly amplify that flow.
Platforms gate “nonprofit” features by classification, not by content. YouTube Nonprofit Program, Google Ad Grants, Meta Charitable Giving, TikTok for Good — all use the IRS 501(c)(3) determination as the eligibility credential. Algorithmic amplification, free advertising, fundraising tools, and platform fee reductions flow to the classification, not to content review.
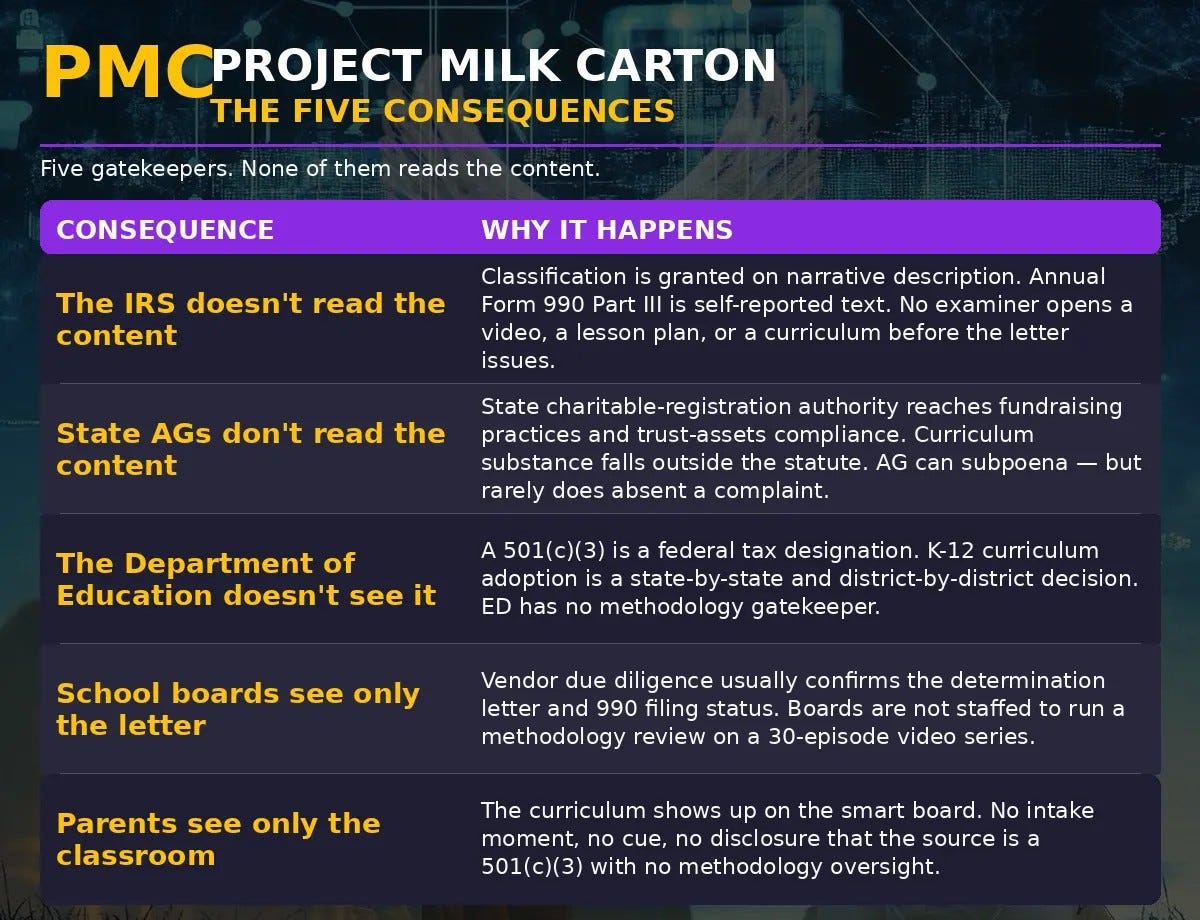
The combined effect: a politically aligned operation that files correctly as educational, writes a broad mission statement, and avoids the few operational tripwires (campaign intervention, private inurement, excessive unrelated business income) can run indefinitely, at scale, with the public-benefit presumption intact, across every regulator that matters.

Part IV — The Scale
How many 501(c)(3) organizations classify themselves under an educational exempt purpose?
IRS data shows roughly 1.9 million active 501(c)(3)s as of this writing. A large share of them, by the IRS’s own master-file purpose codes, classify under the “educational” exempt purpose on their determination letters.
The genuine educational sector, colleges and museums included, runs to hundreds of billions of dollars a year in reported revenue.
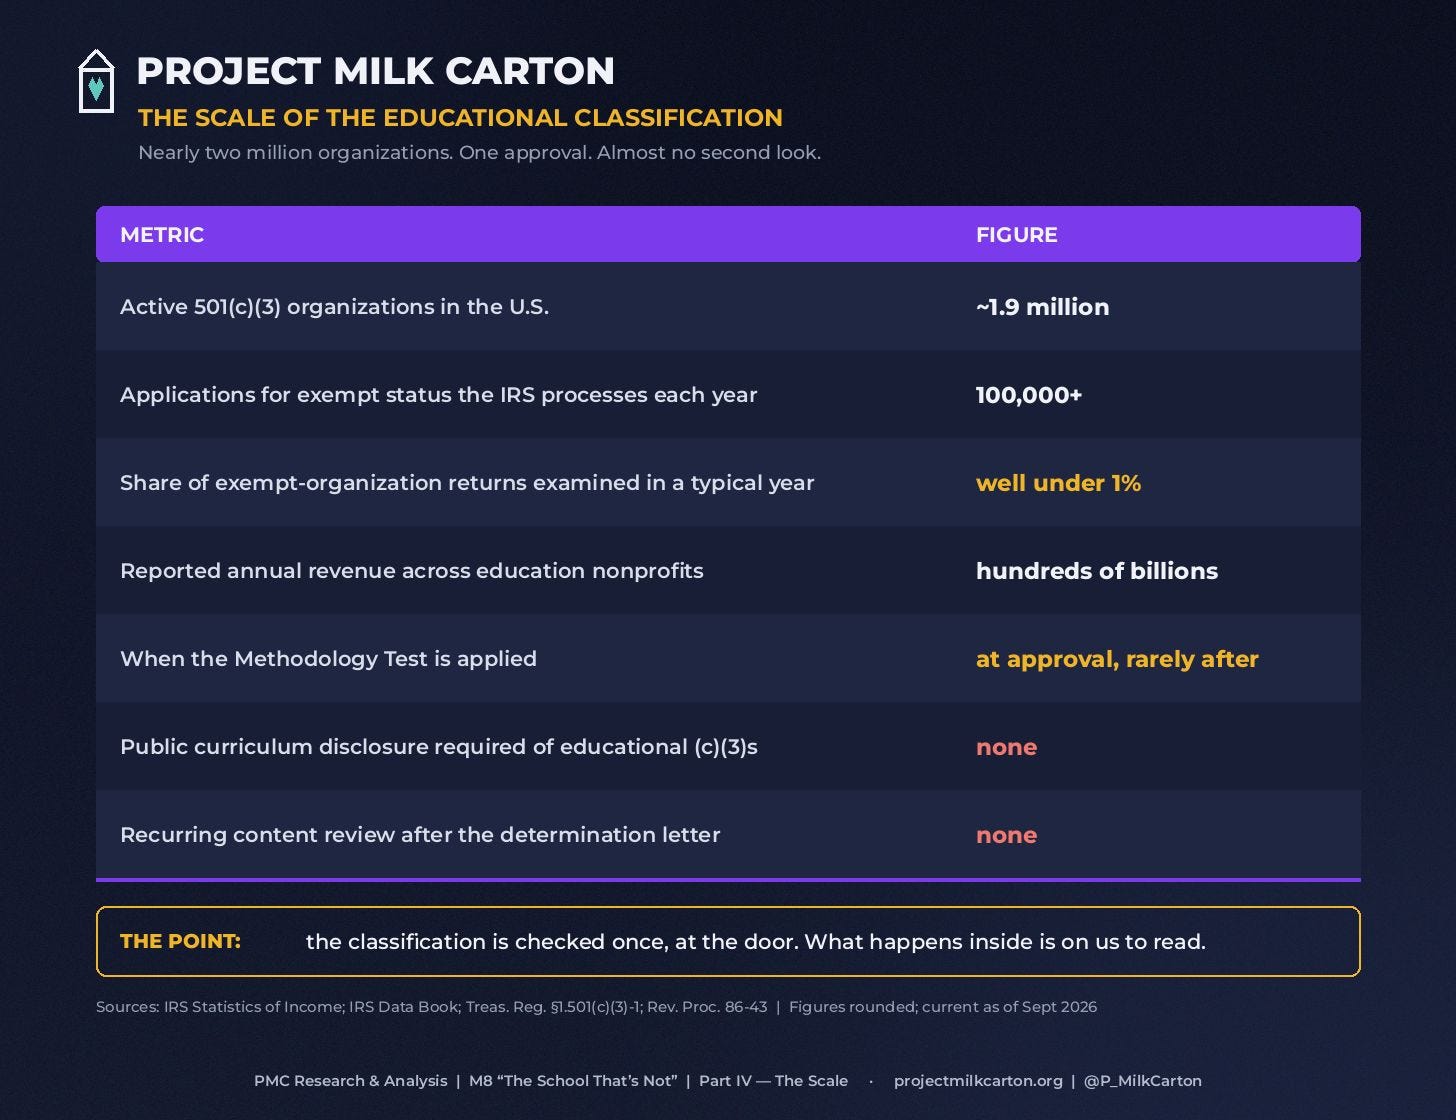
The vast majority of that number is genuine: colleges and universities, public school foundations, accredited museums, scientific research institutes, libraries, literacy programs, accredited trade schools. These organizations apply the Methodology Test honestly, publish full and fair factual material, and teach.
The abuse subset is a fraction. But the fraction is weaponized. An operation that captures even a small sliver of that enormous pool, under the educational classification banner, has more fiscal leverage than most federal programs designed to influence public opinion.
Part V — Why This Move Beats The Alternatives
If a political operation’s goal is to shape public discourse on a given subject, the operator has a menu of legal structures. The 501(c)(3) educational classification is almost always the winning choice.
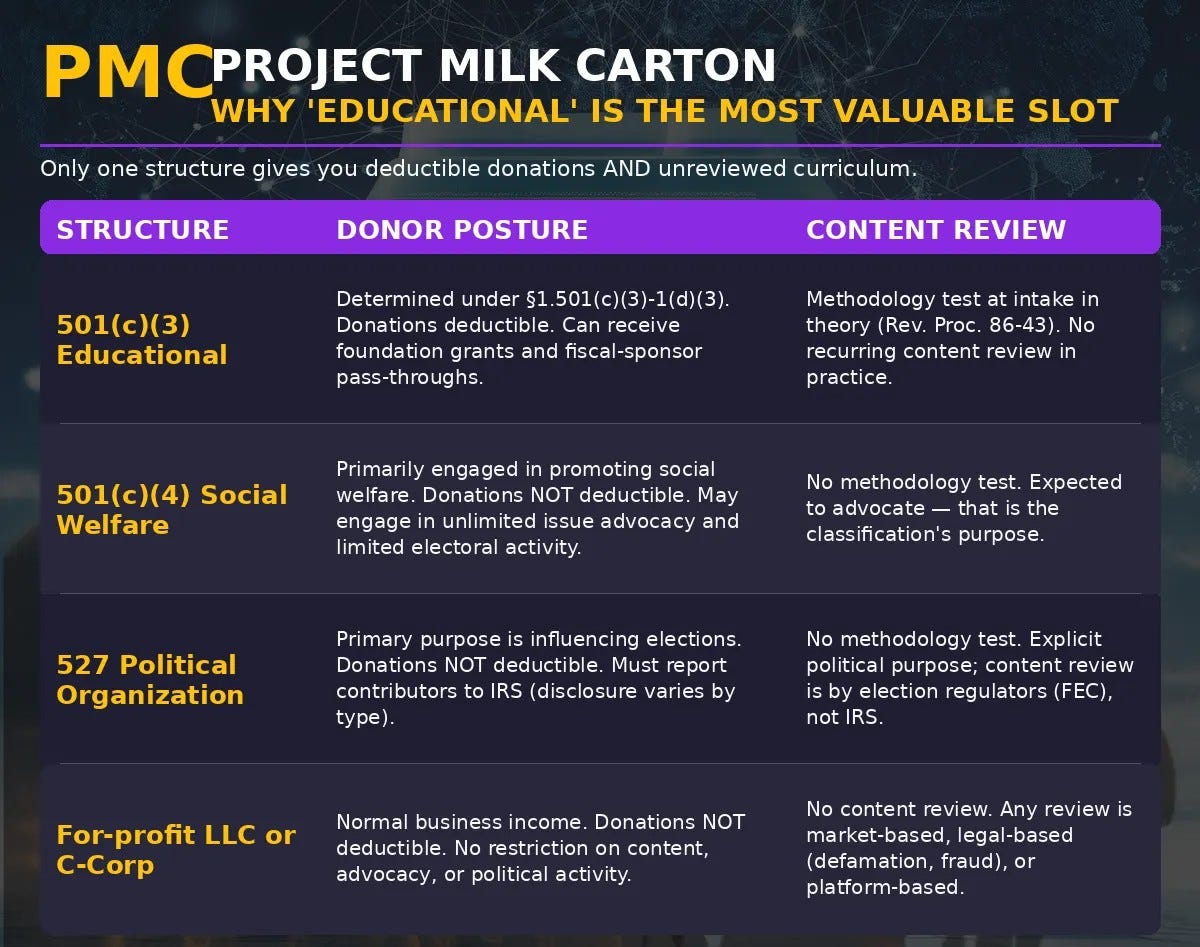
The (c)(3) educational shell is the only structure that combines donor-deductibility, dark-money tolerance, and platform nonprofit access. For an operator whose goal is to move political content through educational channels with tax-subsidized funding, no other structure offers the same economics.
This is not a drafting oversight. The architecture is the attraction.
Part VI — Legitimate Uses (Where the Move Is Not the Move)
A 501(c)(3) educational classification is not evidence of abuse. The overwhelming majority of educational (c)(3)s do exactly what the IRS intended: they teach.
Accredited schools, colleges, and universities — educational classification is statutory and appropriate.
Public-broadcasting educational programming — PBS member stations, public-radio station foundations, educational media producers.
Libraries, museums, cultural institutions — classification flows from mission.
Peer-reviewed research institutes — Brookings, RAND, the Hoover Institution, academic research centers.
Professional-development nonprofits — teacher-training programs that adopt curriculum standards.
Literacy and ESL programs — direct instruction to specific learners.
A 501(c)(3)’s classification does not determine whether it is abusing the category. Content, method, and program service accomplishments do. This module is not an accusation against the classification itself. It is a field guide for readers to distinguish the genuine education from the cover.
Part VII — Case A: The Video Curriculum (Red-Coded)

PragerU (Prager University Foundation) is a 501(c)(3) charitable organization, EIN 27-1763901, headquartered in Sherman Oaks, California. Its determination letter classifies it under 501(c)(3) educational purposes.
What the public record shows. Per its Form 990 filings, PragerU reported total revenue of approximately $71 million in FY2022, with program service expenses of approximately $44 million. The Part III Program Service Accomplishments describes the organization’s mission as producing and distributing “free educational videos that promote American values.” The content itself consists primarily of 5-minute video “lessons” presented by named hosts who advocate for specific positions on economics, history, American foundational principles, and contemporary policy.
What happened in 2023-2024. Florida’s Department of Education approved PragerU Kids materials in July 2023 as supplemental curriculum, meaning teachers may use the videos but are not required to. The Oklahoma State Department of Education, under Superintendent Ryan Walters, announced an ongoing partnership with PragerU in September 2023. Several other states followed; PragerU also announced it was an approved vendor in Texas, though state education officials there denied it had been approved. For its part, PragerU states on its own site that it is not an accredited university, and describes its work as “a free alternative to the dominant left-wing ideology in culture, media, and education”; its chief executive has publicly defended the classroom materials as high-quality and pro-American.
What the classification means in this case. The 501(c)(3) educational status allows PragerU to receive tax-deductible contributions, obtain employer-matched donations, appear on YouTube’s Nonprofit Program, and hold itself out publicly as an educational organization for school-district adoption purposes. Whether the content of the videos — which take named positions on contested public-policy questions — satisfies the Methodology Test of Revenue Procedure 86-43 is a question the IRS has not publicly addressed since the organization’s determination.
A citizen applying the Methodology Test to any specific PragerU video would ask: are viewpoints presented as conclusions (factor 1)? Are opposing factual contexts substantially engaged (factor 2)? Does the tone and delivery permit independent judgment (factor 4)? The answers inform the classification question. The IRS has not revisited them.
Part VIII — Case B: The Fiscal Sponsor Network (Blue-Coded)

New Venture Fund is a 501(c)(3) charitable organization, EIN 20-5806345, headquartered in Washington, D.C. It is the largest of the affiliated 501(c)(3) and (c)(4) entities that were managed by Arabella Advisors, a for-profit management services company. (Arabella announced it was winding down in 2025; the nonprofit funds continue to operate.) The other affiliated entities include the Hopewell Fund, the Sixteen Thirty Fund (c)(4), and the Windward Fund.
What the public record shows. Per its Form 990 filings, New Venture Fund reported total revenue of approximately $950 million in FY2022. Its Part III Program Service Accomplishments describes its mission as supporting “research and educational initiatives” in public health, climate, democracy, and related fields.
The fiscal sponsorship model. New Venture Fund and its affiliated entities operate as fiscal sponsors, meaning they host dozens to hundreds of named “projects” under their single (c)(3) determination. A project is typically a campaign, an advocacy operation, or an initiative that does not have its own separate (c)(3) classification — instead, it operates under New Venture Fund’s educational/charitable exemption. ProPublica’s Nonprofit Explorer and watchdog documentation, along with investigative reporting by the Atlantic, the Washington Post, and The New York Times, have documented dozens of named projects, many of which function as policy advocacy operations.
What the classification means in this case. Because every named project operates under the parent’s 501(c)(3) educational classification, projects that would not independently qualify for educational status receive the benefits of the umbrella classification: donor deductibility, grant eligibility, platform access, public-interest presumption. A donor giving $100,000 to a specific named project inside New Venture Fund’s umbrella receives a deduction identical to a donor giving $100,000 to a traditional educational research institute. Whether the sponsored activity individually would satisfy the Methodology Test is a question that does not arise at the filing stage, because the parent classification covers it.
A citizen applying the Methodology Test to any specific project inside the fiscal-sponsor umbrella would ask: does this project, on its own, meet factors 1-4? Many do. Some do not. The classification does not distinguish, and the public filing does not break out program service accomplishments at the project level beyond what the sponsor chooses to disclose.
Part IX — The Legal Architecture

Five legal instruments hold the educational (c)(3) architecture in place.
Internal Revenue Code §501(c)(3) — the statutory classification. “Corporations … organized and operated exclusively for religious, charitable, scientific, testing for public safety, literary, or educational purposes, or to foster national or international amateur sports competition … or for the prevention of cruelty to children or animals.”
Treasury Regulation §1.501(c)(3)-1(d)(3) — the educational definition, discussed above. The “full and fair exposition” standard.
Revenue Procedure 86-43 — the Methodology Test. The four-factor application procedure, binding on IRS examining agents.
Section 501(h) election — an optional election that caps lobbying expenditures at specific dollar amounts. A (c)(3) that does not make the election is subject to the “substantial part” test, which is deliberately vague and has historically been under-enforced.
Section 4945 expenditure responsibility — applies to private foundations making grants to non-(c)(3) recipients. Does not apply to grants between (c)(3)s, including from a foundation to an educational (c)(3). The rule that would require due-diligence on the purpose of the expenditure simply does not trigger in the (c)(3)-to-(c)(3) flow.

These five instruments were drafted as the guardrails. In combination, they create a system where classification is the credential, the credential is self-policing, and self-policing rarely reaches back to audit operational content.
Part X — What You Can Do: The 5-Minute Educational (c)(3) Audit
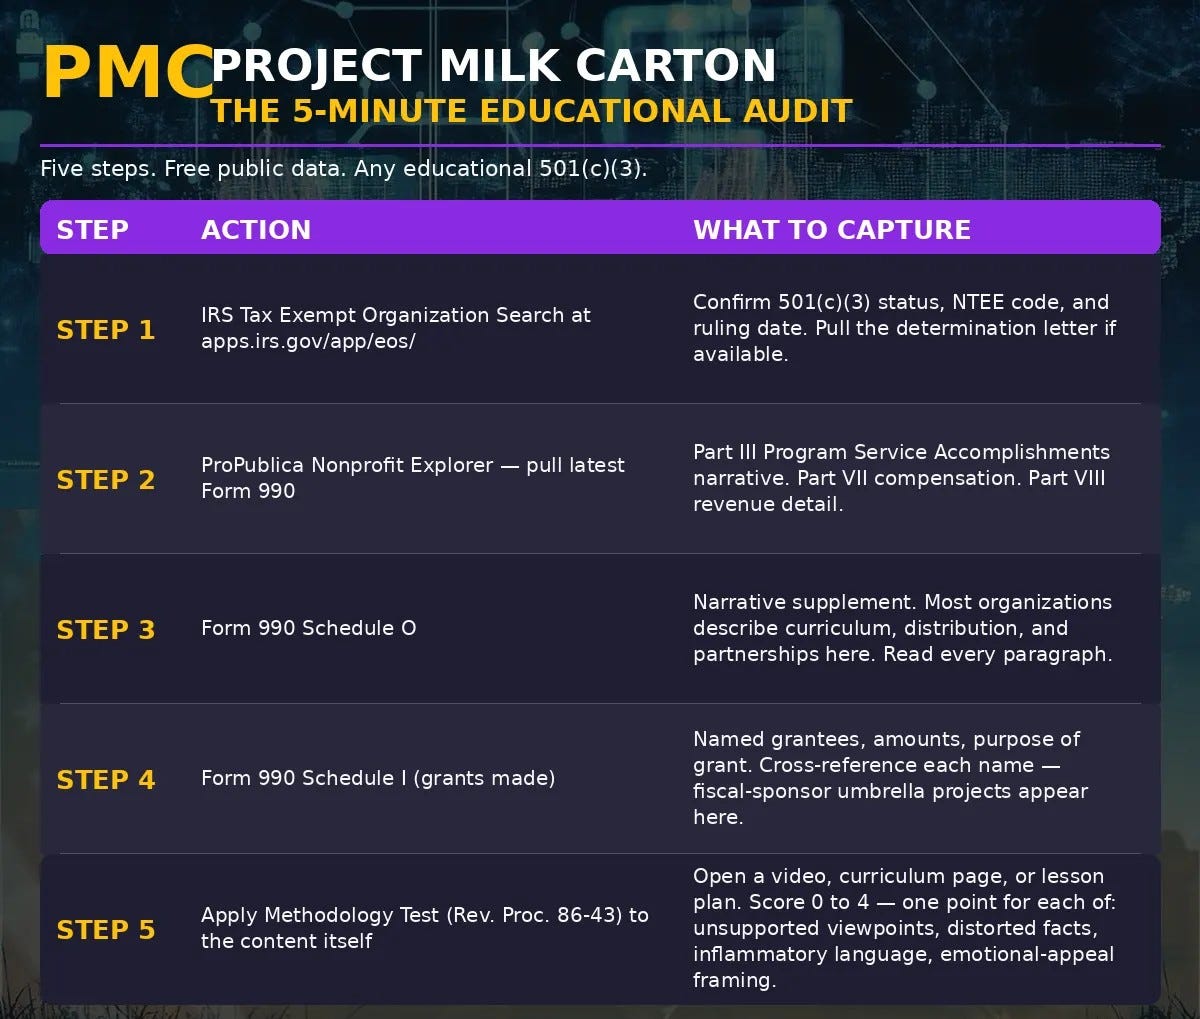
The audit below is the citizen-facing companion to this article. It takes five minutes per (c)(3) and tells you whether an organization classified as “educational” is actually teaching, or is running cover content.
Step 1 — Pull the Form 990. Go to ProPublica Nonprofit Explorer or the IRS Tax Exempt Organization Search. Enter the organization’s name or EIN. Download the most recent publicly filed Form 990.
Step 2 — Read Part III, Program Service Accomplishments. This is where the organization describes, in narrative form, what it actually does with the money. Compare the Part III narrative to the mission statement on page 1. Does the program service match the broad mission, or is it a specific partisan project under a broad umbrella?
Step 3 — Read Schedule O. Schedule O is the “supplemental information” attachment where the organization is required to explain any Yes/No question on the return that needs clarification. Look for the language of advocacy, campaign-adjacent activity, or politically coded terminology.
Step 4 — Cross-check Schedule I (grants to other organizations). Schedule I lists domestic grantees above the reporting threshold. If the organization is a grantmaking educational (c)(3), look at the grantee list. Are the grantees universities and research institutes? Or are they advocacy operations, affiliated (c)(4)s, or fiscal-sponsored projects?
Step 5 — Apply the Methodology Test to a sample of content. Go to the organization’s website, YouTube channel, or most recent annual report. Pick one piece of content — a video, a report, a curriculum module. Ask the four questions:
Are viewpoints presented as conclusions without meaningful factual support?
Are facts distorted or selectively omitted?
Are emotional appeals substituted for reasoned arguments?
Is the delivery calibrated to permit an informed independent judgment?
If the answer to any of factors 1-3 is YES, or factor 4 is NO, the content likely would not satisfy the Methodology Test under rigorous IRS review. The classification may still be valid on paper. But you now have the structural visibility to see what the classification itself does not reveal.
Module 8: Citizen Action Card, Read the Curriculum
Part XI — The Next Move
The game has nine moves. You have now seen six.
M3 taught you the Anonymous Donor — DAF stacking. M4 taught you the Russian Doll — entity laddering. M5 taught you Fiscal Sponsorship — borrowed (c)(3) status. M6 taught you the Foreign Principal Pass-Through. M7 taught you Delaware LLC Opacity — the corporate ghost. M8, this one, teaches you “Educational” Classification Abuse — the purpose shield.
Module 9 — Personnel Overlap Coordination. How the same three names appear as officers, directors, and advisors across ostensibly unrelated entities — the personnel pattern that proves the architecture is a single operation, not a constellation of independent actors.
Once you can read personnel, you can read the whole system.
Sources and Citations
Revenue Procedure 86-43: the IRS Methodology Test for educational organizations
IRS Publication 557: Tax-Exempt Status for Your Organization
ProPublica Nonprofit Explorer: the public IRS filings for every organization named in this article
The Hill: the Florida and Oklahoma classroom approvals, 2023
Stateline via Oklahoma Voice: the multi-state adoption picture and the disputed Texas claim
InfluenceWatch: New Venture Fund and the fiscal sponsorship model
Chronicle of Philanthropy: Arabella Advisors winds down, 2025
Project Milk Carton · Module 8 · 501(c)(3) · EIN 33-1323547
This article is the journalism deliverable for Module 8. For the citizen audit toolkit — how to apply the Methodology Test yourself — see the companion Citizen Action Card.